Home › Articles and News › 2026 Condo Financing Changes for Portland Veteran Buyers
2026 Condo Financing Changes for Portland Veteran Buyers
What to know about HOA reserves, insurance, and approval before you buy a condo
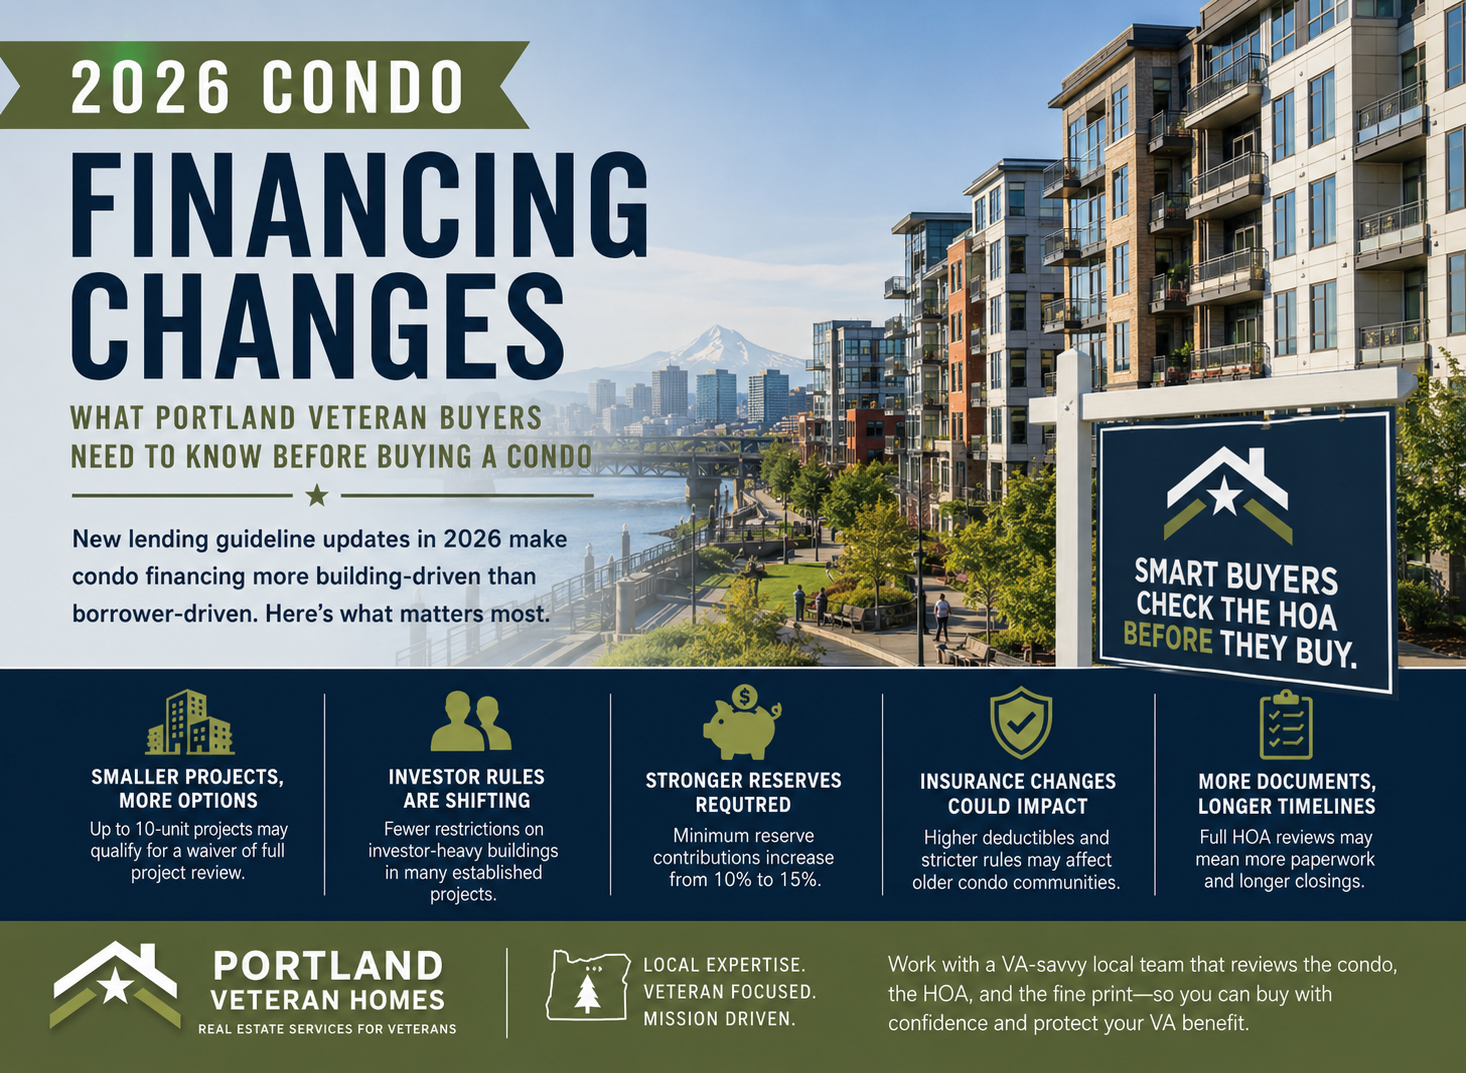
If you're a veteran planning to buy a condo in Portland or the surrounding metro in 2026, new lending guideline changes could affect your purchase, your financing options, and your future resale value. Here's what's changing, and how to protect yourself.
Condo Financing Is Becoming Building Driven
Many of these updates come from conventional condo financing guidelines, but they still matter for VA buyers. HOA financial health, insurance, reserve funding, and future marketability are more important than ever.
The reality is simple: condo financing is becoming more building driven than borrower driven.
Even highly qualified veteran buyers with strong VA eligibility need to pay close attention to the condo association itself.
Why These Changes Matter for Veteran Buyers
VA financing remains one of the strongest home loan programs available:
No Down Payment
Eligible VA buyers may be able to buy with zero down.
No Monthly PMI
VA loans don't require monthly private mortgage insurance.
Competitive Rates
VA rates are often very competitive with other loan options.
Assumable Financing
VA loans can be assumable, which can help resale value. See Portland VA assumable homes.
But condos are different. Approval often depends as much on the HOA's reserves, insurance, budget, and project condition as it does on you.
1. Small Condo Projects May Become Easier to Finance
One of the biggest improvements is that projects with up to 10 units may now qualify for a waiver of full project review. Previously, most of these exceptions were limited to projects with four units or fewer. This could help buyers looking at:
- Townhouse style condos
- Boutique condo communities
- Duplex style condo ownership setups
- Smaller attached projects in Portland, Beaverton, Hillsboro, and Vancouver
If a condo doesn't qualify for VA financing, conventional financing may now be more accessible as a backup option.
2. Investor Heavy Condo Projects May Open Up
Older guidelines often restricted financing when investors owned more than half of the units. Many of those limits are being relaxed for established projects, which may help buyers considering:
- Downtown Portland condos
- Pearl District properties
- South Waterfront buildings
- Vancouver waterfront condos
- Mixed owner occupied and rental communities
3. HOA Reserve Requirements Are Getting Stricter
This is one of the most important changes to watch. Minimum HOA reserve contributions are increasing from 10% to 15% of the budget. Some associations may need to:
- Raise HOA dues
- Postpone maintenance projects
- Issue special assessments
- Address deferred maintenance
Weak HOA reserves can create resale and financing problems later, even if the condo is VA approved today.
4. Insurance Changes Could Affect Older Communities
Master policy deductible rules are tightening, and many older buildings already face higher insurance costs and stricter underwriting. Review:
- Master policy deductible amounts
- Roof coverage details
- Loss assessment exposure
- Whether you need additional HO-6 coverage
Older Portland area communities with aging roofs, siding, or deferred maintenance may face extra lender scrutiny.
5. Condo Closings May Take Longer
The limited review process is gradually going away, so more purchases may require a deeper look at HOA documents. Lenders may ask for:
- HOA budgets
- Reserve studies and statements
- Insurance certificates
- Board meeting minutes
- Delinquency reports
- Pending assessment disclosures
The smartest approach is to review condo documents before you write an offer whenever possible.
The Most Important Question: Is the Condo VA Approved?
This is still the first question every veteran condo buyer should ask. Check the VA approved condo list for Portland and read my Portland VA condo guide. Even though many of these rules mainly affect conventional loans, they still shape your backup financing options, resale strength, appraisal risk, and HOA stability.
What Makes a Strong Condo Purchase in 2026
- Healthy HOA reserves
- No pending special assessments
- Updated roofs and exterior systems
- Manageable insurance deductibles
- Low deferred maintenance
- Strong owner occupancy
- Clear VA or conventional financing eligibility
Buying a condo with a VA loan? I help veteran buyers review approval status, HOA financials, financing options, and red flags before writing an offer. Call 503.997.4169 or schedule a free call.
Keep Reading
Portland VA Condo Guide
How VA condo approval works in Portland.
Read the guide ›VA Approved Condo List
Search VA approved condo projects in the Portland area.
View the list ›VA Appraisal Requirements
What the appraiser checks, and what to do if value comes in low.
Read the guide ›Portland VA Assumable Homes
Take over a seller's VA loan at a lower rate.
Learn more ›Ready to Start Your Home Search?
Browse homes in the Portland metro and across the river in Vancouver, Camas, and Ridgefield.
Frequently Asked Questions
Can I buy a condo in Portland with a VA loan?
Yes, as long as the condo project is approved by the VA. Check the VA's condo approval list before you write an offer, and review the HOA's budget, reserves, and insurance.
What happens if the condo isn't VA approved?
The HOA can apply for VA approval, which takes time, or you may be able to use conventional or FHA financing instead. Recent conventional guideline changes may make some smaller and investor heavy projects easier to finance.
Why do HOA reserves matter so much?
Healthy reserves pay for big repairs like roofs and siding. Weak reserves can lead to higher dues, special assessments, and future financing problems that hurt resale value.
Will buying a condo take longer to close?
It can. More lenders are asking for HOA budgets, reserve studies, insurance certificates, and meeting minutes, so reviewing condo documents before you write an offer helps avoid delays.
More Guides for Veterans
Meet Your Veteran Realtor
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call, text, or email? 503.997.4169 · Text Us · troy [at] nwrealtysource [dot] com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP®, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. This page is general information, not legal, tax, or lending advice.