Enter These Numbers for a VA Loan
Home Price and Down Payment
Start with the price range you're shopping. If you have full entitlement, enter 0 percent down. A down payment is optional, and 5 or 10 percent down lowers your funding fee.
Interest Rate
Use a current quote from a VA lender rather than a national average, since your rate depends on credit, points, and loan type. Oregon veterans can also compare the ODVA home loan.
Property Taxes
Use the actual annual tax from the listing or county records. Oregon taxes are based on assessed value, which is often well below market value, so the real bill can be lower than you'd guess. Washington taxes follow assessed market value.
Homeowners Insurance
Get a real quote on the home if you can. Rates vary by home age, roof, and location, and premiums in Washington have risen faster in recent years.
Mortgage Insurance
Enter $0. VA loans have no monthly mortgage insurance, which is one of the biggest savings compared with FHA and conventional loans.
HOA Dues
Condos and many townhomes have monthly dues. Add them so your total payment is realistic, and check my VA condo guide before you shop.
What a Calculator Can't Tell You
Residual Income
VA lenders look at how much money you have left each month after your bills and housing payment. It's one reason VA loans perform so well, and it can matter as much as your payment.
Debt to Income
Lenders use 41 percent debt to income as a VA benchmark, but strong residual income and credit can support more. A lender can tell you where you really stand.
Closing Costs
VA limits some fees veterans can be charged, and sellers can help with closing costs. See my funding fee and closing cost guide.
A Lower Rate Option
Some sellers have VA loans you can take over at their original rate. See Portland VA assumable homes.
Want real numbers on a real home? Send me a listing and I'll help you estimate taxes, insurance, and HOA dues, and connect you with a VA lender for a rate quote. Call 503.997.4169 or schedule a free call.
Your Next Steps
Get Started With a VA Loan
Pre-approval, your COE, and every step from offer to closing.
Read the guide ›VA Home Loan Guide
Loan limits, funding fees, credit, and how VA loans work in Portland.
Read the guide ›ODVA vs. Federal VA Loan
Compare Oregon's state veteran loan with a federal VA loan.
Compare ›VA Jumbo Loans
Buying above the county limit with a VA loan.
Read the guide ›VA IRRRL Refinance
Already have a VA loan? See how a streamline refinance works.
Read the guide ›Multifamily Investment Calculator
Run the numbers on a duplex, triplex, or fourplex VA house hack.
Open the calculator ›Frequently Asked Questions
Does a VA loan have PMI?
No. VA loans don't have monthly private mortgage insurance, even with zero down. Set the mortgage insurance field in the calculator to $0. Most buyers pay a one time VA funding fee instead, unless they're exempt.
How much down payment do I need for a VA loan?
With full VA entitlement, no down payment is required. Putting 5 or 10 percent down is optional, but it lowers the funding fee and your monthly payment.
Should I include the VA funding fee in the calculator?
If you plan to finance the funding fee, add it to the loan amount so your payment estimate is accurate. Veterans who receive VA disability compensation are exempt and can skip it.
What property tax amount should I use for a Portland home?
Use the actual annual property tax shown on the listing or county records. In Oregon, taxes are based on a home's assessed value, which is often well below the sale price, so a simple percentage of the price can overstate your taxes.
Can the seller pay my closing costs on a VA loan?
Yes. Sellers can pay a buyer's normal closing costs, and VA also allows seller concessions of up to 4 percent of the price for things like the funding fee or paying off debts. How much you can ask for depends on the market and the home.
Is there a VA loan limit?
Veterans with full entitlement have no VA loan limit, though your lender still sets a maximum based on your income and credit. If you have part of your entitlement tied up in another VA loan, county loan limits apply. See my VA home loan guide for current limits.
More Guides for Veteran Buyers
What Veterans Say About Working With Us
Veteran buyers who used their VA loan with our team
"If you're a vet THIS IS THE PLACE. Troy walked me through every step and made me feel important."
"We had a lot of trouble completing the process when we tried to use our VA Loan. So I looked online and found Troy, who knows well the ins and outs of the VA process."
"I chose Troy to help me purchase a home because of his expertise and knowledge. I found Troy well informed, efficient, professional, and personable."
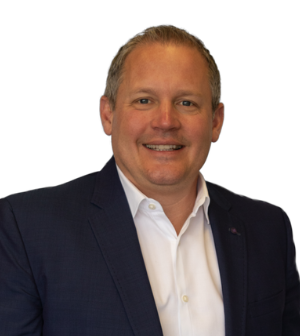
Meet Your Veteran Realtor
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call, text, or email? 503.997.4169 · Text Us · troy [at] nwrealtysource [dot] com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP®, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. This page is general information, not legal, tax, or lending advice.
Please note: Portland Veteran Homes is a private, veteran-owned real estate company and is not affiliated with the U.S. Department of Veterans Affairs. Loan programs, limits, and market conditions change, so confirm details with your lender.