Home › VA Home Loan Guide › VA Loan Requirements
VA Loan Requirements Checklist
What it takes to qualify in Portland and SW Washington, in plain English
Before you start touring homes, it helps to know exactly what it takes to qualify. Here's a plain English checklist of VA loan requirements for buyers in the Portland metro and SW Washington: service, credit, income, occupancy, and the property itself. For loan limits, funding fees, and the step by step buying process, see my Complete VA Home Loan Guide.
What's Covered on This Page
Service and Eligibility Requirements
Your eligibility comes from your service record. In general, you may qualify if you meet one of these:
Active Duty
You're currently serving and have at least 90 continuous days of active service.
Veterans
You served at least 24 continuous months, or the full period you were called to active duty (at least 90 days), and were discharged under conditions other than dishonorable. Shorter service can qualify after a service connected disability or certain other discharges.
National Guard and Reserve
You have six years of creditable service, or at least 90 days of active duty service, including at least 30 consecutive days.
Surviving Spouses
You may qualify if your spouse died in service or from a service connected disability, and you haven't remarried, or you remarried on or after age 57.
Your Certificate of Eligibility (COE) confirms all of this, and your lender can usually pull it in minutes. My COE and DD-214 guide explains what to have ready, and the VA eligibility page lists the service dates for every era.
Credit, Income, and Debt Requirements
The VA sets the framework, but each lender adds its own standards. Here's what most Portland area lenders look for:
Credit Score
The VA has no minimum credit score. Most lenders want somewhere in the 580 to 620 range, and some ask for 620 or higher on larger loan amounts.
Stable Income
Lenders typically look for two years of steady employment or income. Military pay, VA disability compensation, retirement pay, and BAH can all count.
Debt to Income Ratio
The VA uses 41% of your gross monthly income as a guideline for total debt payments. It isn't a hard cap, and lenders can go higher when your residual income is strong.
Residual Income
This is the VA's own test: the money left each month after your mortgage, taxes, debts, and estimated living costs. The amount required depends on family size and region, and Oregon and Washington fall in the VA's West region.
Past Credit Events
Lenders typically want about two years after a Chapter 7 bankruptcy or a foreclosure. With a Chapter 13, you may qualify after 12 months of on time plan payments with trustee approval.
Shopping for a loan? Read my 3 Homebuyer Tips on Credit Scores and Choosing the Right Mortgage Lender.
Step one for VA buyers
Think you meet the requirements? Find out in 2 minutes
Get pre-qualified in about 2 minutes. No cost, no obligation, and we match you with a local trusted lender.
Down Payment and Money at Closing
Down Payment
With full entitlement, there's no down payment at any price your lender approves. With partial entitlement, you can put $0 down up to the 2026 county limit of $832,750 in Multnomah, Washington, Clackamas, and Clark counties.
Earnest Money
When your offer is accepted, you'll deposit earnest money, typically about 1% of the price. It's credited toward your closing costs, and any unused amount comes back to you at closing.
Seller Concessions
Sellers can contribute up to 4% of the price toward items like prepaid taxes and insurance, the VA funding fee, or paying off collections, on top of normal closing costs. In a competitive market, you may need to build this into your offer.
Funding Fee
Most buyers pay a one time VA funding fee, which can be rolled into the loan. Veterans receiving VA disability compensation don't pay it. See the full rate table in my VA Home Loan Guide.
Occupancy Requirements
A VA loan is for the home you'll live in. You'll certify that you intend to occupy it as your primary residence, generally within about 60 days of closing. If you're deployed or on orders, your spouse can usually meet the requirement for you.
That rule also opens a great option: you can buy a 2 to 4 unit property and live in one unit. My guide to buying a duplex with a VA loan and the Duplex and Fourplex Investment Calculator show how the numbers work.
Property Requirements
The home itself has to meet the VA's Minimum Property Requirements: it must be safe, structurally sound, and sanitary. The VA appraisal checks this along with the value.
- Eligible homes: single family homes, townhomes, new construction, owner occupied 2 to 4 unit properties, and condos in a VA approved project.
- Condos: the whole condo project must be VA approved. Check with the VA Approved Condo List.
- Pest inspection: the VA now requires a wood destroying insect inspection statewide in Oregon for VA appraisals issued on or after June 25, 2025. In Clark County, it depends on what the appraiser finds.
- Home inspection: not required by the VA, but I recommend one for every buyer. It shows the home's true condition and gives you leverage to negotiate repairs.
- Fixer uppers: homes needing work may still qualify with a VA renovation loan.
Want the details? See Minimum Property Requirements for VA Loans and Appraisal Requirements for VA Loans.
The bottom line: most veterans qualify more easily than they expect. The best first step is a quick pre-approval, so you know your budget before you fall in love with a home.
 Watch the VideoVA Home Loan Benefits for Portland Metro VeteransNo down payment is just the start.
Ready to Start Your Home Search?
Browse homes in Portland, Beaverton, Hillsboro, Tigard, and Lake Oswego, or across the river in Vancouver, Camas, and Ridgefield.
Frequently Asked Questions
Who is eligible for a VA home loan?
Veterans, active duty service members, National Guard and Reserve members who meet the service requirements, and certain surviving spouses. Your discharge must be under conditions other than dishonorable.
What credit score do I need for a VA loan?
The VA doesn't set a minimum credit score. Most lenders look for a score somewhere in the 580 to 620 range, and some ask for more on larger loan amounts.
Is there a maximum debt to income ratio for a VA loan?
The VA uses 41% as a guideline, not a hard cap. Lenders can approve higher ratios when you have strong residual income, which is the money left over each month after your major expenses.
Do I need a down payment for a VA loan?
Not with full entitlement. You can buy with $0 down at any price your lender approves. If you have partial entitlement, you can still put $0 down up to the 2026 county limit of $832,750.
Do I have to live in the home?
Yes. A VA loan is for your primary residence, and you generally need to move in within about 60 days of closing. If you're deployed, your spouse can usually meet the occupancy requirement.
Can I get a VA loan after a bankruptcy or foreclosure?
Often, yes. Lenders typically want about two years after a Chapter 7 bankruptcy or a foreclosure. With a Chapter 13, you may qualify after 12 months of on time plan payments with trustee approval.
Does Oregon require a pest inspection for VA loans?
Yes. The VA now requires a wood destroying insect inspection statewide in Oregon for VA appraisals issued on or after June 25, 2025. In Clark County, ask your lender, since Washington rules depend on the appraisal.
Can I use a VA loan for a duplex or fourplex?
Yes. You can buy a 2 to 4 unit property with a VA loan as long as you live in one of the units as your primary residence.
More VA Loan Guides
What Veterans Say About Working With Us
Veteran buyers who used their VA loan with our team
"His knowledge of the real estate business, current markets, resale priorities were top notch during the purchase of our new home and the sale of our old."
"If you're a vet THIS IS THE PLACE. Troy walked me through every step and made me feel important."
"We had a lot of trouble completing the process when we tried to use our VA Loan. So I looked online and found Troy, who knows well the ins and outs of the VA process."
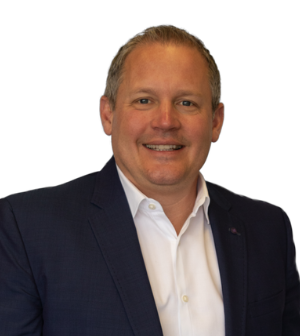
Meet Your Veteran Realtor
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call, text, or email? 503.997.4169 · Text Us · troy [at] nwrealtysource [dot] com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP®, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. This page is general information, not legal, tax, or lending advice.