Home › Veteran Loans › VA Home Loan
How the VA Loan Works in Portland and SW Washington
The complete Portland VA loan guide: limits, funding fees, credit, and the buying process
Everything a veteran, active duty service member, or surviving spouse needs to know about buying a home in the Portland metro and SW Washington with a VA loan: 2026 loan limits, funding fees, credit, the buying process, jumbo financing, and assumable loans. This page is long on purpose. Bookmark it, jump to the section you need, or call me and I'll walk you through it.
What's Covered on This Page
- VA Loan Basics: $0 Down, No PMI
- Video: VA Home Loan Benefits
- 2026 VA Loan Limits for Portland Metro Counties
- The VA Funding Fee Explained
- Credit, Eligibility & Your Certificate of Eligibility
- How the Buying Process Works, Step by Step
- VA Jumbo Loans for Higher Priced Homes
- VA Assumable Loans: A Hidden Advantage
- Video: Turning a Low VA Rate Into Offers
- Frequently Asked Questions
VA Loan Basics: $0 Down, No PMI
A VA loan is a mortgage backed by the U.S. Department of Veterans Affairs. It's available to eligible veterans, active duty service members, National Guard and Reserve members, and certain surviving spouses. The VA guarantee lets lenders offer terms that are hard to match with conventional financing, which matters even more with today's interest rates.
$0 Down
With full entitlement, you can buy with no down payment and 100% financing at any price your lender approves. Buyers with partial entitlement can still put $0 down up to the 2026 county limit of $832,750.
No PMI
VA loans never require monthly private mortgage insurance. On a typical Portland metro purchase, that can save you several hundred dollars a month compared with a low down payment conventional loan.
Seller Concessions
Sellers can contribute up to 4% of the sales price toward things like prepaid items, the VA funding fee, and paying off collections or judgments at closing, on top of normal closing costs. In a competitive market, you may need to build this into your offer price.
Reusable Benefit
Your VA benefit never expires and can be used again and again. Entitlement is usually restored once a previous VA loan is sold and paid off.
Earnest money still applies. When your offer is accepted, you'll deposit earnest money as good faith, typically about 1% of the sales price. It's credited toward your closing costs, and any unused amount comes back to you at closing.
Step one for VA buyers
Find out what you can buy with your VA loan
Get pre-qualified in about 2 minutes. No cost, no obligation, and we match you with a local trusted lender.
Video: VA Home Loan Benefits for Veterans in Portland Metro
A walkthrough of the core VA loan benefits for veterans and active duty service members buying in the Portland metro, and why so many eligible buyers never use them.
Wondering whether you qualify? Keep reading, or reach out to me directly.
2026 VA Loan Limits for Portland Metro Counties
VA loan limits work differently than most buyers expect. If you have full entitlement, meaning you've never used a VA loan or any prior VA loan has been paid off and the home sold, there's no VA cap on how much you can borrow with zero down. Your ceiling is set by what your lender will approve based on your income, credit, and the appraised value.
The county limit only matters if you have partial entitlement, meaning you currently have an active VA loan or a prior VA loan went to foreclosure. In that case, the limit determines how much of your remaining entitlement you can use with zero down.
| County | State | 2026 Limit |
|---|---|---|
| Multnomah County | Oregon | $832,750 |
| Washington County | Oregon | $832,750 |
| Clackamas County | Oregon | $832,750 |
| Clark County | Washington | $832,750 |
The 2026 limit rose from $806,500 in 2025 to $832,750 for most U.S. counties, including the entire Portland metro. No county in our Oregon or SW Washington service area has a higher limit. Limits are set each year by the FHFA, so always confirm the current figure with your lender.
The VA Funding Fee Explained
The VA funding fee is a one time charge that goes to the VA, not your lender. It keeps the program running without monthly mortgage insurance. You can pay it at closing or roll it into your loan.
| Down Payment | First Use | Subsequent Use |
|---|---|---|
| Less than 5% | 2.15% | 3.30% |
| 5% to 9.99% | 1.50% | 1.50% |
| 10% or more | 1.25% | 1.25% |
Rates shown are for purchase loans. Your lender will confirm the exact fee for your loan.
Who Is Exempt
Veterans receiving VA compensation for a service connected disability, active duty Purple Heart recipients, and surviving spouses receiving Dependency and Indemnity Compensation don't pay the funding fee. That alone can save thousands at closing.
May Be Tax Deductible
Starting with the 2026 tax year, mortgage insurance premiums, which include the VA funding fee, can again be deducted by homeowners who itemize. Ask your tax professional whether it applies to you.
Credit, Eligibility & Your Certificate of Eligibility
VA loans have more flexible underwriting than conventional financing, but lenders still set their own minimum standards.
- The VA doesn't set a minimum credit score, but most lenders look for a score in the 580 to 620 range.
- Your Certificate of Eligibility (COE) confirms your entitlement, and your lender can usually pull it for you in minutes. My COE and DD-214 guide explains how.
- Eligibility generally covers active duty service members, veterans, qualifying National Guard and Reserve members, and certain surviving spouses.
- Owner occupied 2 to 4 unit properties qualify too. See my guide to buying a duplex with a VA loan.
- Most VA buyers choose a 30 year or 15 year fixed rate loan, though VA adjustable rate loans are also available.
Want to protect your score while you shop? Read my 3 Homebuyer Tips on Credit Scores, and estimate your payment with the VA Mortgage Calculator.
How the Buying Process Works, Step by Step
A VA purchase in the Portland metro follows a predictable path. Here's what it looks like from pre-approval to closing.
Get Pre-approved
Your lender confirms your Certificate of Eligibility and pre-approves you for a loan amount, so you have a realistic budget before you tour homes. Not sure who to call? Read Choosing the Right Mortgage Lender.
Make an Offer
When you find the right home, your offer will include earnest money, typically around 1% of the price, as a show of good faith. It's credited toward your closing costs.
Home Inspection
The VA doesn't require an inspection, but I recommend one for every buyer. It shows you the home's true condition and gives you leverage to negotiate repairs. I also watch for issues that could trip up the VA's minimum property requirements.
VA Appraisal
Your lender orders a VA appraisal, which confirms the value and checks that the home meets VA standards. I help buyers spot problems early and work with sellers to fix items before they hold up the loan.
Underwriting and Closing
VA purchases in the Portland area are closing in about 30 to 45 days from an accepted offer. Scheduling the inspection fast and ordering the appraisal early keeps you on track. My Contract to Closing guide walks through every milestone.
VA Jumbo Loans for Higher Priced Homes
Because veterans with full entitlement have no VA loan limit, a "VA jumbo loan" simply means a VA loan above the conforming loan amount. In Portland, where many desirable neighborhoods sit above $832,750, this matters more than buyers expect.
- With full entitlement, you don't need a down payment no matter the loan amount.
- With an active VA loan or entitlement lost to a prior VA foreclosure, you may need a down payment.
- Lenders often require a credit score of 620 or higher for larger loan amounts, though this varies.
- Service requirements are the same as for any VA loan.
- Manufactured homes generally aren't eligible for VA jumbo financing.
- Owner occupied 2 to 4 unit properties can work with VA jumbo financing too.
Why this matters in Portland: With metro home prices well into the $500,000s, and neighborhoods in Lake Oswego, West Linn, Portland's west side, and parts of SW Washington often running much higher, full entitlement buyers are often in jumbo territory without realizing it. The good news is your zero down benefit doesn't go away just because the price is high.
VA Assumable Loans: A Hidden Advantage
One of the most overlooked features of a VA loan is that it's generally assumable. A qualified buyer, veteran or not, may be able to take over the seller's existing VA loan, including the interest rate, remaining balance, and terms. With so many Portland area homeowners holding rates well below today's market, that can be a real advantage on both sides of the deal.
For Buyers
Assuming a lower rate loan can mean a much lower monthly payment than a new mortgage at today's rates, sometimes hundreds of dollars a month less.
For Sellers
A low rate assumable loan can help your home stand out in a market where affordability is the buyer's biggest concern.
The catch: the buyer only takes over the remaining loan balance, so they need cash or secondary financing to cover the difference between that balance and the price. Assumptions also take longer, often 45 to 90 days. I cover all of it, including how your entitlement is affected when a non veteran assumes your loan, on my Portland VA Assumable Homes page.
Video: How Portland Sellers Turn a Low VA Rate Into Offers
If you have a low VA rate, a qualified buyer may be able to assume it. Here's how that can set your Portland home apart, and what to watch for before you market it that way.
Questions after watching? Reach out and we'll talk through whether an assumable strategy fits you as a buyer or a seller.
Ready to See What You Qualify For?
Browse homes in Portland, Beaverton, Hillsboro, Tigard, and Lake Oswego, or across the river in Vancouver, Camas, Ridgefield, and Battle Ground.
Frequently Asked Questions
Do I really not need a down payment for a VA loan in Portland?
If you have full VA entitlement, that's right. There's no VA loan limit and no down payment required at any price, as long as your lender approves the loan amount based on your income, credit, and the appraised value.
What is the 2026 VA loan limit for Multnomah, Washington, Clackamas, and Clark counties?
The 2026 limit is $832,750 in all four counties. It only affects buyers with partial entitlement, meaning those who still have an active VA loan or had a prior VA loan go to foreclosure.
How much is the VA funding fee?
For a first time VA purchase with less than 5% down, the funding fee is 2.15% of the loan amount. It drops with a larger down payment, and veterans receiving VA disability compensation don't pay it at all.
What credit score do I need for a VA loan?
The VA doesn't set a minimum credit score, but most lenders look for a score somewhere in the 580 to 620 range. Larger loan amounts may require a higher score.
How long does closing take on a VA loan in Portland?
Most VA purchases in the Portland metro close in about 30 to 45 days from an accepted offer, as long as the inspection and appraisal are scheduled promptly.
Can I use a VA loan on a home priced above the county limit?
Yes, if you have full entitlement. The county limit doesn't cap how much you can borrow with zero down. It only applies to buyers with partial entitlement.
Can I buy a duplex or fourplex with a VA loan?
Yes. You can buy a 2 to 4 unit property with a VA loan as long as you live in one of the units as your primary residence.
Is a VA assumable loan a real opportunity in this market?
For the right buyer and seller, yes. Many Portland area homeowners locked in VA rates well below today's market, and a buyer who assumes that loan can get a much lower payment. Plan for the equity gap and a longer timeline.
Can I use a VA loan in both Oregon and Washington?
Yes. Your VA benefit isn't tied to a state, so you can shop homes on both sides of the Columbia River in the Portland metro and SW Washington.
More VA Loan Guides
What Veterans Say About Working With Us
Veteran buyers who used their VA loan with our team
"If you're a vet THIS IS THE PLACE. Troy walked me through every step and made me feel important."
"We had a lot of trouble completing the process when we tried to use our VA Loan. So I looked online and found Troy, who knows well the ins and outs of the VA process."
"I chose Troy to help me purchase a home because of his expertise and knowledge. I found Troy well informed, efficient, professional, and personable."
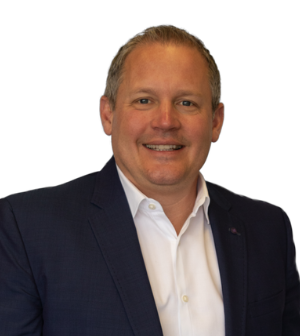
Meet Your Veteran Realtor
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call, text, or email? 503.997.4169 · Text Us · troy [at] nwrealtysource [dot] com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP®, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. This page is general information, not legal, tax, or lending advice.