Buyer Resource Center › The Home Buying Process › 3 Homebuyer Tips on Credit Scores and Inquiries
Your credit score is one of the biggest factors in your mortgage. It helps decide whether you're approved, what rate you get, and what you'll pay in fees. The good news is that a few smart habits can protect your score from the day you start shopping until the day you get your keys. Here's what I tell every veteran and military buyer I work with in the Portland metro and SW Washington.
3 Tips to Protect Your Score
Know the Difference Between Hard and Soft Inquiries
A soft inquiry, like checking your own score or a lender's pre-qualification check, doesn't affect your credit at all. A hard inquiry happens when you apply for credit, such as a mortgage, car loan, or credit card. A hard inquiry can lower your score by a few points, stays on your report for two years, and can only be pulled with your permission.
Keep Your Credit Steady Until Closing
Your lender will check your credit again right before closing. Opening a new credit card, financing furniture or appliances, buying a car, or running up balances on your existing cards can lower your score or change your debt to income ratio. Either one can raise your rate or even stop your loan at the finish line.
Shop Lenders in a Short Window
Comparing lenders is smart, and it won't hurt your score much if you do it within a short period. Credit scoring models treat several mortgage inquiries made close together as rate shopping and count them as a single inquiry. Some newer models allow up to 45 days, but older versions still used by many mortgage lenders use a 14 day window.
The bottom line: Your credit doesn't have to be perfect to buy a home with a VA loan, but every point helps. Check your reports early, fix any errors, keep things steady once you apply, and do your lender shopping in a tight window. If your score needs work, I'm happy to connect you with lenders who can map out a plan.
Frequently Asked Questions
What credit score do I need for a VA loan?
The VA doesn't set a minimum credit score, but most lenders set their own minimums, and higher scores usually get better rates and terms. A VA lender can tell you where you stand and what would help most.
Will checking my own credit lower my score?
No. Checking your own credit is a soft inquiry and never affects your score. You can get free reports from Equifax, Experian, and TransUnion at AnnualCreditReport.com.
How much does a hard inquiry hurt my credit score?
Usually just a few points. Hard inquiries stay on your report for two years, but their impact fades over time. Multiple mortgage inquiries made within a short window are generally counted as one.
Will getting pre-approved by more than one lender hurt my credit?
Not much, if you do it within a short period. Credit scoring models group mortgage inquiries made close together as rate shopping. To be safe, try to get all your quotes within about two weeks.
Can I buy furniture or a car before closing?
It's best to wait. Your lender rechecks your credit before closing, and new debt can lower your score or change your debt to income ratio. Make big purchases after you have the keys.
How can military members protect their credit?
Active duty service members can place a free active duty alert on their credit reports and get free credit monitoring from the three bureaus. Both help protect you from identity theft, especially during deployments and PCS moves.
Keep Reading
Understand the Differences Between Mortgage Providers
Banks, credit unions, brokers, and VA specialists compared.
Read more ›15 Ways to Save Money for a Down Payment
Even with a zero down VA loan, cash for closing costs and reserves helps.
Read more ›8 Expensive Homebuyer Mistakes
Costly missteps veteran and first time buyers can easily avoid.
Read more ›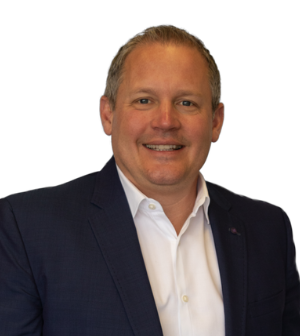
Meet Your Veteran Realtor
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call or email? 503.997.4169 · troy@nwrealtysource.com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. Content adapted in part from ABR® consumer resources. This page is general information, not legal, tax, or lending advice.