Home › Articles and News › VA Home Buying and Selling Guide
VA Home Buying and Selling Guide
Every guide Portland and SW Washington veterans need, in one place
Whether you're buying your first home with a VA loan or selling a home you bought with one, this is your starting point. I've organized my most helpful guides for veterans in the Portland metro and SW Washington below.
Buying a Home With a VA Loan
Complete VA Home Loan Guide
$0 down, funding fees, loan limits, and the step by step process.
Read the guide ›VA Loan Requirements
Service, credit, income, occupancy, and property requirements.
Read the guide ›Home Buyer Resource Center
37 guides from credit scores to closing day.
Read the guide ›2026 VA Loan Limits
County limits and why full entitlement means no limit.
Read the guide ›First-Time Homebuyer Tips
Five tips for buying your first home.
Read the guide ›From Contract to Closing
Every milestone between your accepted offer and the keys.
Read the guide ›Selling Your Home as a Veteran
Veteran Seller Advantage Program
How I help veteran sellers get top dollar.
Read the guide ›Why List With Us
Our marketing plan and veteran seller discounts.
Read the guide ›See Your Home's Value
Get a free market analysis of your home.
Read the guide ›VA Assumable Loans
How a low rate VA loan can help your home sell.
Read the guide ›Veteran Downsizing Guide
Planning a smaller home for retirement.
Read the guide ›Senior Veteran Resource Center
Guides for senior veterans and their families.
Read the guide ›Remember: a VA loan is a benefit you earned through your service. Only eligible veterans, service members, and certain surviving spouses can get one, and it's still the strongest way for most veterans to buy a home.
Ready to Start Your Home Search?
Browse homes in the Portland metro and across the river in Vancouver, Camas, and Ridgefield.
Real Estate Questions and Answers
Here are answers to the questions I hear most from buyers and sellers, from appraisals and closing costs to foreclosures and taxes. Tap a topic to jump to it, then tap any question to open the answer.
Home Value, Appraisals, and Market Value · Closing Costs and Closing Day · Co-ops · Condominiums and Townhouses · Fixer Uppers and Home Improvements · Foreclosures · Getting Started · Home Inspections · Insurance · Negotiating and Closing the Best Deal · New Homes and Vacation Homes · Property Taxes · Tax Matters · Working With a Veteran REALTOR®
Home Value, Appraisals, and Market Value
How do you determine how much a home is worth?
The short answer: a home is worth what a buyer will pay for it. Everything else is an estimate. In a hot seller's market, when demand is high and inventory is low, homes can sell above the asking price as buyers compete. Fair market value is set when the buyer and seller reach a meeting of the minds on price.
Are there standard ways to determine how much a home is worth?
Yes. A comparative market analysis and an appraisal are the two most common and reliable ways.
A REALTOR® can prepare a comparative market analysis, an informal estimate of value based on recent sales of similar homes nearby, plus the asking prices of homes on the market now. It's one of the best ways to avoid overpaying.
A licensed appraiser visits the home, notes the size, rooms, improvements, quality, and condition, and then compares it to recent sales to estimate its value. Lenders require an appraisal before approving a mortgage. On a VA loan, the VA assigns the appraiser and sets the fee, which is usually several hundred dollars.
What is the difference between list price and sales price?
The list price is the seller's advertised or asking price. It's the seller's estimate of what they'd like to get. The sales price is what the home actually sells for. Comparing the list price to recent sales of similar homes is a good way to tell whether it's fair.
What about appraised value and market value?
Appraised value is the appraiser's estimate based on comparable sales, the home's condition, and other factors. Market value is the price the home brings at a given point in time, once the buyer and seller agree on price. On a VA loan, the appraised value appears on the VA's Notice of Value.
Closing Costs and Closing Day
What are closing costs?
Closing, or settlement, costs are expenses beyond the price of the home. Both buyers and sellers have some of them. Who pays what depends on local custom and what you negotiate. They usually include title insurance, lender fees, escrow fees, prepaid property taxes and insurance, and recording fees. Your lender gives you a Loan Estimate early on and a Closing Disclosure at least three business days before closing.
Is it possible to save on closing costs?
Yes. Closing costs often run 2 to 5 percent of the price, but here are ways to lower them:
- Negotiate with the seller. On a VA loan, the seller can pay your closing costs, plus up to 4 percent of the price in concessions.
- Use the VA's fee limits. The VA caps the lender's origination charge at 1 percent and limits what veterans can be charged.
- Consider a lender credit. A slightly higher rate can cover some of your costs if cash is tight.
- Shop lenders. Every lender prices differently, so compare Loan Estimates.
Is there anything I should know about closing day?
In Oregon and Washington, an escrow company usually handles your signing, often a day or two before the sale records. A few tips:
- Protect yourself from wire fraud. Before you wire money, call your escrow officer at a number you already know to confirm the instructions. Never trust wiring instructions that arrive by email alone.
- Bring a photo ID. A driver's license or passport works.
- Do a final walkthrough. Confirm the home is in the condition you agreed to and any repairs were done.
- Set up utilities. Arrange to have water, power, gas, and internet moved into your name on the day you take possession.
Co-ops
What are co-ops?
In a cooperative, or co-op, you don't own your unit as real property. You own shares in a corporation that owns the building, and those shares give you the right to live in a specific unit. Co-op loans are written much like mortgages, and owners can usually deduct their share of mortgage interest and property taxes.
A board of directors elected by the residents runs the co-op. Owners pay a monthly fee for their share of operating costs and must follow the co-op's rules, which can limit pets, rentals, and who can buy in. Co-ops are uncommon in the Portland area, and financing options for them are limited, so talk to your lender early.
What are the benefits of a co-op?
Co-ops often have low turnover, resident control over the building, and limits on investor ownership. They come in many forms, including apartments, townhouses, and senior housing. Learn more from the National Association of Housing Cooperatives at coophousing.org.
Condominiums and Townhouses
What is a condominium?
In a condominium, you own your own unit, the space inside the walls, floors, and ceilings, plus a shared interest in the common areas such as the land, hallways, and parking. Each owner pays monthly dues to the homeowners association for maintenance, repairs, and the building's insurance.
Why buy a condo?
Condos can be an easier way into homeownership when a single family home is out of reach. They're popular with first-time buyers, singles, and empty nesters, and they free you from yard work and most exterior upkeep. Many also offer amenities like a gym or pool.
To use a VA loan, the condo project must be VA approved. See my VA Condo Guide.
How do you choose a good condo?
Look for a well maintained building and pay close attention to the association's finances. Things to check:
- The latest budget, financial statement, and reserve study.
- Whether major repairs are coming, what they'll cost, and whether reserves can cover them.
- The bylaws, rules, and CC&Rs, which can limit pets and rentals.
- Meeting minutes, plus any lawsuits or disputes.
- The ratio of owners to renters.
How do townhouses differ from condominiums?
A townhouse shares one or more walls with its neighbors, but the owner usually owns both the home and the land under it. In a condo, owners share ownership of the land. Some townhouse communities have shared amenities and an HOA, much like a condo. Some townhouses are legally condos, so check how the property is set up.
Are condos good investments?
They can be a good first step into homeownership. Like any home, value depends on the location, the building's condition, and the health of the association. A well run association with healthy reserves makes a big difference.
What are the pros and cons of owning a townhouse?
Pros: less exterior maintenance, no neighbors above or below you, and often a greater sense of security. Cons: HOA dues if there is an association, less privacy than a detached home, and limits on exterior changes.
Fixer Uppers and Home Improvements
Where can you find fixer uppers?
They're in nearly every neighborhood. What sets them apart is price: they sell for less than nearby homes because they've been poorly maintained or neglected. A classic strategy is to find the least desirable home in the most desirable neighborhood, then make sure the repairs fit your budget.
If you're new to this, start with a home that needs mostly cosmetic work, such as paint, flooring, fixtures, and landscaping. And remember, a price that looks too good to be true usually has a reason.
Is buying one a good idea in a less established area?
It depends on your tolerance for risk. Up and coming neighborhoods have given many first-time buyers an affordable way into homeownership, and many close in areas have seen a strong resurgence. Do your homework on the neighborhood's direction before you buy.
How do I determine the value of a distressed property?
Start with a comparative market analysis of similar homes, both sold and for sale. Then get a realistic estimate of what repairs will cost. You can also research comparable sales in county records. If the home is a foreclosure or bank owned, ask the seller for any reports they have.
What guidelines should I use to find a contractor?
- Ask friends, family, neighbors, and your agent for referrals.
- Hire only licensed contractors. Check a contractor's license and complaint history with the Oregon Construction Contractors Board or Washington Labor & Industries.
- Get written estimates from more than one contractor and call recent references.
- Ask for proof of liability insurance and, if they have employees, workers' compensation coverage.
- Never pay a large deposit at the first meeting, and get a written contract.
What kind of return can I expect from home improvements?
It varies by project. Remodeling magazine's annual Cost vs. Value Report compares what common projects cost with what they add at resale. Exterior projects like garage doors, entry doors, and siding often recoup the most, while large additions and upscale remodels usually recoup less. Improvements also make a home more livable and more appealing to future buyers.
How can I finance work needed on a fixer upper?
Options include cash savings, a home equity loan or line of credit, a cash out refinance, or a renovation loan that rolls the repairs into your purchase loan. Shop carefully, and use high rate financing only as a last resort.
Does the federal government offer home improvement programs?
Yes. Among the most popular:
- VA renovation loans. Veterans can finance a purchase plus repairs in one VA loan. See my VA Renovation Loan Guide.
- FHA 203(k). Finances the purchase or refinance and rehab of one to four unit homes.
- FHA Title I. Insured loans for basic livability improvements.
- USDA repair loans and grants. For eligible low income homeowners in rural areas.
What about state and local governments?
Oregon Housing and Community Services and the Washington State Housing Finance Commission offer programs for buyers and homeowners, and many cities and counties offer repair programs for specific neighborhoods or income levels. Your city's housing or community development office is a good place to start.
Are special tax breaks available for historic rehabilitation?
Income producing properties listed on the National Register of Historic Places may qualify for a 20 percent federal historic tax credit for qualified rehabilitation costs. Oregon also has a Special Assessment program for historic properties. Learn more from the National Trust for Historic Preservation at savingplaces.org, and talk with a tax professional.
Foreclosures
What causes a foreclosure?
A lender forecloses, or takes back, a property when the owner stops paying the mortgage. Common causes include job loss, illness, divorce, and unexpected expenses. Unpaid property taxes or HOA dues can also lead to foreclosure.
If you're a veteran behind on a VA loan, call the VA's loan technicians at 877-827-3702 as early as possible. Read about the new VA Partial Claim Program.
Where can I find foreclosure properties?
Bank owned homes, also called REOs, are usually listed with local agents and show up in a normal home search. Your agent can also watch for pre foreclosures and short sales. Homes sold at trustee auctions are listed with the trustee or on auction websites.
Buying foreclosures isn't easy. Experienced investors compete for them, so get as much information as you can before you make an offer.
What happens at a trustee sale?
Most Oregon and Washington foreclosures are non judicial, handled by a trustee instead of a court. After the owner defaults, the trustee records and mails a notice of default and sets a sale date, usually at least 120 days out. At the sale, the property goes to the highest bidder, who must pay in cash or a cashier's check and receives a trustee's deed. These sales attract seasoned investors, so come prepared.
What are the disadvantages of buying foreclosures?
- At a trustee sale, there's no financing. You need cash.
- The title should be checked first, or you could inherit liens.
- You often can't see inside before an auction.
- Foreclosures are sold as is, so you can't go back to the seller for repairs.
- Bank and estate sellers are often exempt from the seller disclosures other sellers must give.
How do I find government owned homes?
HUD sells homes it takes back on FHA loans at hudhomestore.gov, and the VA sells homes it takes back on VA loans through its contractor. Both are offered through licensed real estate brokers, so your agent can submit an offer for you.
What are the guidelines for buying HUD homes?
HUD homes are sold as is, with no warranties. Owner occupants get an early window to bid before investors, and your offer must include an earnest money deposit. If a home needs work, HUD prices it accordingly, and FHA 203(k) financing can help. Learn more at hud.gov.
What about VA foreclosures?
Anyone can buy a VA owned home, veteran or not. But only eligible veterans, service members, and certain surviving spouses can use a VA loan. A non veteran buying a VA owned home needs another type of financing.
Why is location so important?
Location is still the single most important factor in choosing a home. It drives value and desirability. Think about your lifestyle, property taxes, schools, commute, services, recreation, and the feel of the community. Visit at different times of day and talk to neighbors.
Getting Started
What are the advantages of owning a home?
You control your living space, you build equity as you pay down the loan and as the home appreciates, and a fixed rate mortgage keeps your principal and interest payment steady, unlike rent. Equity can later help with college, a move up home, or retirement. Owning can also bring tax benefits if you itemize.
What is the first step to buying a home?
Make sure you're ready, financially and personally. Do you have steady income? Are your debts manageable? Do you have money for closing costs and reserves for repairs? Then get pre-approved with a lender so you know your budget. My Home Buyer Resource Center walks through every step.
How much can I afford?
Lenders look at your debt to income ratio, and on a VA loan, residual income, which is what's left each month after your major bills. Your lender can tell you your maximum, but the better number is the monthly payment you're comfortable with, including taxes, insurance, and upkeep. Try my VA Mortgage Calculator.
Should I save for my dream home or start with a starter home?
Saving for the perfect home can take years. A starter home lets you begin building equity now, which can help you move up later. With a VA loan, you can often buy with no down payment, and your benefit can be used again in the future.
Should I add on to my home or buy a new one?
Weigh the cost, your needs, and what adds value. An addition can cost less than moving and lets you stay in a home you love. Questions to ask:
- Can you pay with cash, or will you need a loan?
- How much equity do you have?
- Is there room to expand, and do local zoning and building rules allow it?
- Are there homes for sale that would meet your needs?
Home Inspections
What does a home inspector do?
A home inspector is a trained professional who checks the condition of a home, focusing on its structure, roof, and major systems like plumbing, electrical, and heating. An inspector doesn't set value; that's the appraiser's job. The inspection usually happens right after your offer is accepted. In Oregon, home inspectors must be certified by the Construction Contractors Board.
Should I hire a home inspector?
Yes. The VA appraisal is not a full inspection. Your offer should include an inspection contingency, which lets you ask for repairs, renegotiate, or walk away if serious problems turn up. In older Portland homes, I also recommend a sewer scope, and consider radon testing too.
How do I select a home inspector?
Hire one who is licensed or certified, experienced, and well reviewed. Membership in a trade group like the American Society of Home Inspectors (ASHI) or InterNACHI is a plus. Your agent can give you several names.
Do I need to be at the inspection?
It isn't required, but it's a very good idea. You can ask questions as you go and hear an objective opinion from someone with no stake in the sale.
Insurance
What does homeowners insurance cover?
A standard policy covers your home and belongings against fire, theft, and many other events. It also includes liability coverage if someone is hurt on your property, and living expenses if you have to move out during repairs. Your lender will require it.
What kind of home insurance should I get?
A standard policy works for most homes, but it doesn't cover earthquakes or floods. In the Portland area, earthquake coverage is worth a look, and your lender will require flood insurance if the home is in a flood zone. Ask about replacement cost coverage for your home and belongings, and coverage for a home business if you have one.
What is condo and co-op insurance?
Owners need two policies: the association's master policy, which covers the building and common areas and is paid through your dues, and your own policy, often called an HO 6, which covers your belongings, interior improvements, and liability.
What about title insurance?
Title insurance protects against problems with the title, such as old liens or ownership disputes. The lender's policy protects the lender. An owner's policy protects you. In Oregon, the seller usually pays for the owner's policy.
Is private mortgage insurance necessary?
On most conventional loans with less than 20 percent down, lenders require private mortgage insurance (PMI), and it can usually be dropped once you have enough equity. Don't confuse PMI with mortgage life insurance, which pays off your loan if you pass away.
VA loans have no PMI. Instead, most veterans pay a one time VA funding fee, which can be rolled into the loan. Veterans who receive VA disability compensation are exempt.
Negotiating and Closing the Best Deal
Is it possible to buy a home below market price?
Yes, but it takes time and patience. Good targets include foreclosures, fixer uppers, and new homes a builder needs to sell. Bargains are easiest to find in a slower market.
Are low ball offers a good idea?
Any offer can be presented, but one far below the asking price can offend a seller and end the conversation. Unless the home is overpriced, it will probably be rejected. Research recent sales first, and learn what matters to the seller. A quick closing or flexible move out date can be worth more to some sellers than price.
Can you negotiate interest rates?
Rates are mostly set by the market, but you can compare lenders, ask about points and lender credits, and sometimes negotiate fees. A seller can also pay to buy down your rate as part of your offer, which is very popular right now.
What are some negotiating tips?
- Learn the seller's motivation. A seller who must move soon may be more flexible.
- Know value. Compare the asking price to recent sales.
- Stay flexible. A take it or leave it stance can sour a deal.
- Each time you give a little, ask for something in return, like repairs or closing costs.
- Use your strengths. A pre-approval and a flexible closing date make your offer stronger.
- Keep emotions out of it.
What contingencies should appear in the offer?
Contingencies let you cancel without losing your earnest money if something goes wrong. Most offers include a financing contingency and an inspection contingency, and VA offers include the VA appraisal. The contract also spells out the seller's duties, such as delivering clear title and keeping the home in the same condition until closing.
Does the seller take the furnishings when the home is sold?
Usually, yes. Fixtures, items permanently attached to the home like built in shelves, light fixtures, and the furnace, stay unless the contract says otherwise. Anything not attached, like a washer and dryer, is negotiable, so put it in writing.
Do I need an attorney to buy a home?
Oregon and Washington don't require one; escrow companies handle most closings. Read your contract carefully, and if you have legal questions, especially about contingencies or unusual terms, talk to a real estate attorney.
New Homes and Vacation Homes
Can you negotiate the price of a new home?
Often, yes. Builders are usually most flexible at the start and end of a project. If they won't lower the price, ask for upgrades, a better lot, or help with closing costs or a rate buydown.
Should I hire a home inspector for a new home?
Yes. Even new homes can have problems. Consider a pre drywall inspection plus a final inspection, and ask the builder for copies of the city's inspection reports.
What else should I consider when buying a new home?
- Talk to owners who already live there, or who bought from the builder before.
- Ask about plans for nearby roads, schools, and shopping, and review the zoning.
- Read the HOA rules, which may limit colors, landscaping, and changes.
- Bring your own agent on your first visit. Many builders won't work with your agent if you register without one.
Do builders provide financing?
Many builders have a preferred lender and offer incentives, like help with closing costs or a lower rate, for using it. Compare the offer with another lender so you know the real value.
Should I buy a vacation home?
A second home can be for enjoyment, investment, or future retirement. You can generally deduct mortgage interest and property taxes on a second home if you itemize. If you rent it out, the tax rules depend on how many days you use it yourself versus rent it, so talk with a tax professional. Make sure you can comfortably carry two homes.
What about a vacation home as an investment?
Like any investment, it carries risk. Consider:
- Can you afford repairs, maintenance, insurance, and utilities?
- What will a property manager or rental platform charge?
- Who will clean and check the home between guests?
- Can you cover the mortgage if it doesn't rent?
- Does the city or county allow short term rentals?
Property Taxes
Why do homeowners pay property taxes?
Property taxes fund local services like schools, libraries, roads, fire, and police. How often values are reassessed varies by state.
How are property tax bills figured?
Property tax is based on the value of your property, not your income. In Oregon, your tax is based on your home's assessed value, which generally can't grow more than 3 percent a year, rather than its full market value. In Washington, it's based on market value. Exemptions, like those for disabled veterans and seniors, can lower your bill. See my Oregon Disabled Veteran Property Tax Exemption guide.
Can I contest my property taxes?
Yes. If you think your value is wrong, you can appeal, usually by a deadline after your tax statement comes out. In Oregon, appeals go to the county's Board of Property Tax Appeals. You'll need evidence such as an appraisal or a comparative market analysis, and I'm happy to prepare one for you.
What is an impound or escrow account?
It's an account your lender sets up to collect part of your property taxes and insurance with each monthly payment, then pays those bills for you. Lenders usually collect a cushion at closing.
Are impound accounts required for all mortgage loans?
VA lenders almost always require one. On conventional loans with at least 20 percent equity, you can often waive it, sometimes for a small fee.
Are property taxes deductible?
Yes, if you itemize, property taxes are deductible on your federal return, subject to the cap on state and local tax deductions. Taxes held in escrow are deductible when they're actually paid. Ask a tax professional how this applies to you.
Tax Matters
How can owning a home pay off at tax time?
If you itemize, you can deduct mortgage interest on up to $750,000 of mortgage debt on your main home and a second home, plus property taxes within the federal limit. If you use part of your home for business, you may qualify for a home office deduction. When you sell your main home, you may be able to exclude up to $250,000 of gain, or $500,000 if married filing jointly.
Are up front fees and closing costs deductible?
Points you pay to buy your home are generally deductible the year you pay them. Points on a refinance are deducted over the life of the loan. Many other closing costs, like title and recording fees, aren't deductible, but they're added to your home's cost basis, which lowers your taxable gain when you sell. So do major improvements.
Are HOA fees deductible?
Generally not on your own home, because they're personal living expenses. If you rent the home out, they're deductible as a rental expense. Special assessments for capital improvements may be added to your cost basis.
Are there tax credits for first-time homebuyers?
Some states offer a Mortgage Credit Certificate (MCC), which gives eligible first-time buyers a federal tax credit for part of their mortgage interest each year. MCCs have income and price limits and usually require that you haven't owned a home in the past three years. Ask your lender which programs are available in Oregon and Washington.
Working With a Veteran REALTOR®
What is the best way to find a REALTOR®?
Ask people you trust who recently bought or sold. Then interview two or three agents about their local knowledge, experience, and availability. For a VA loan, look for an agent who knows VA appraisals and how to write a strong VA offer.
What can I expect from a good REALTOR®?
Competence, responsiveness, and ethics. A good agent takes time to understand your needs, shows homes that fit your budget, knows financing, and shares local market data. They avoid pressure tactics, point out concerns about a property, and treat other agents with respect.
Is there anything I should not tell the seller's agent?
Yes. If you're talking to the listing agent, remember they represent the seller. Don't share your top price or your reasons for buying. That's one of the biggest reasons to have your own buyer's agent.
What does a buyer's agent do?
A buyer's agent represents you, helps you find the right home, and negotiates the best price and terms for you. Since 2024, buyers sign a written agreement with their agent before touring homes, which spells out the services and how the agent is paid. On VA loans, veterans can now pay their own agent if needed. See my guide to why to hire an ABR buyer's agent.
Can I use an agent to buy a newly built home?
Yes, and you should. Your agent can help you compare builders, negotiate price and upgrades, and review the builder's contract. Bring your agent on your first visit, since many builders won't work with an agent you didn't register with.
Why do I need an agent if I can find homes online?
Finding a home is only the beginning. Your agent helps you judge value, write a strong offer, negotiate repairs, and keep everything on track through closing. That matters even more with a VA loan.
Are buyers protected against housing discrimination?
Yes. The federal Fair Housing Act prohibits discrimination based on race, color, religion, sex, disability, familial status, or national origin, and Oregon and Washington laws add more protections. If you believe you've been discriminated against, contact HUD at 1-800-669-9777 or hud.gov/fairhousing.
Tax and legal information here is general and not tax or legal advice. Please talk with a tax professional or attorney about your situation.
Frequently Asked Questions
Can only veterans use a VA loan?
Yes. A VA loan is a benefit for eligible veterans, active duty service members, qualifying National Guard and Reserve members, and certain surviving spouses. A non veteran can sometimes assume an existing VA loan, but can't get a new one.
Where should I start if I'm buying with a VA loan?
Start with a pre-approval from a VA experienced lender, then meet with a buyer's agent who knows VA loans. My Home Buyer Resource Center walks through every step.
I'm a veteran selling my home. Where should I start?
Start with a market analysis of your home's value. If you have a low rate VA loan, it may also be assumable, which can help your home stand out.
More Guides for Veterans
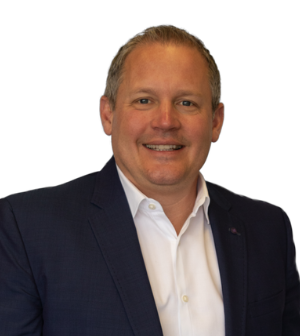
Meet Your Veteran Realtor
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call, text, or email? 503.997.4169 · Text Us · troy [at] nwrealtysource [dot] com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP®, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. This page is general information, not legal, tax, or lending advice.