Home › Veteran Loans › VA Assumable Homes
Portland VA Assumable Homes for Sale
Take Over a Seller's Low Rate VA Loan in Portland & SW Washington
Search Assumable HomesWith rates far higher than a few years ago, VA assumable loans have become one of the best opportunities for Portland area buyers and sellers. Across Portland, Beaverton, Hillsboro, Vancouver, Happy Valley, Ridgefield, Camas, Tigard, and Lake Oswego, some homeowners have VA loans with rates far below today's market, and a qualified buyer may be able to take them over.
Please note: Portland Veteran Homes is a private, veteran owned real estate company and is not affiliated with the U.S. Department of Veterans Affairs. Loan programs, limits, and market conditions change, so confirm details with your lender.
What Is a VA Assumable Loan?
A VA assumable loan lets a qualified buyer take over the seller's existing VA mortgage, including the interest rate, remaining balance, and loan terms. That's extremely valuable when the seller's rate is much lower than what you'd get on a new loan today.
What the Savings Can Look Like
| $350,000 balance, 30 year terms | Monthly principal and interest |
|---|---|
| Assumed VA loan at 2.75% | $1,429 |
| New loan at 6.75% | $2,270 |
| Difference | $841 a month |
This is an illustration. Your actual payment depends on the remaining balance and term of the loan you assume.
Benefits for Buyers
A Lower Rate
Keep the seller's rate instead of today's, which can lower your payment by hundreds a month.
More Buying Power
A lower payment can stretch your budget in competitive Portland neighborhoods.
Less Competition
Many buyers and agents don't understand assumptions, so fewer people compete for these homes.
Low Funding Fee
The VA funding fee on an assumption is just 0.5%, and it's waived for veterans receiving disability compensation.
What Buyers Need to Know
The assumable loan only covers the seller's remaining balance. In many Portland neighborhoods, values have risen, so you'll need to cover the difference between the balance and the price, with cash or sometimes a second loan.
- You still qualify with the loan servicer, with credit, income, and debt to income requirements
- Assumptions often take 45 to 90 days or more, so plan your timeline
- Non veterans can assume a VA loan, but the seller's entitlement then stays tied to the loan
- Experienced VA guidance makes a big difference
How a VA Assumption Works
Find the Home
Search assumable listings or ask me to research a home you like. Listings don't always say the loan is assumable.
Confirm the Loan Details
We verify the rate, balance, and servicer, and estimate the gap you'll need to cover.
Write the Offer and Apply
Your offer is written around the assumption, and you apply with the seller's loan servicer.
Servicer and VA Approval
The servicer reviews your application, and the VA may review the transaction.
Close
You take over the loan, and the seller should receive a release of liability. If you're a veteran substituting entitlement, the seller's entitlement is restored.
Benefits for Portland Veteran Sellers
Selling a home with a low rate VA loan? That loan can be a powerful marketing advantage. Many buyers are looking for any way to lower their payment.
- Stronger buyer interest
- Better online exposure
- A unique selling point in a higher rate market
- An edge over competing homes
Ask about entitlement substitution, so your entitlement is restored if a veteran buyer assumes your loan. See my Veteran Seller Advantage Program.
Example of a VA Assumable Loan Marketing Flyer
Most agents put a home on the MLS and never explain the value of the assumable loan. We market the financing itself, including the existing rate, estimated payment savings, and buyer qualification information. Presented well, a low rate assumable loan can dramatically increase buyer attention.

Real example: a VA assumable loan marketing flyer used for a past client in the Portland and Vancouver metro.
See How a Portland VA Assumable Loan Works
A quick walkthrough of how VA assumable loans work for Portland and SW Washington buyers and sellers, and how a much lower existing rate can mean real monthly savings.
Have questions after watching? Call or text us at 503.997.4169.
Areas We Serve
- Portland
- Beaverton
- Hillsboro
- Tigard
- Tualatin
- Lake Oswego
- West Linn
- Oregon City
- Happy Valley
- Gresham
- Vancouver
- Camas
- Ridgefield
- Battle Ground
- Washougal
Search Portland VA Assumable Homes for Sale
Listings don't always identify assumable VA financing, so contact me if you see a home you like and want help researching the loan.
Frequently Asked Questions
Can a non veteran assume a VA loan?
Yes. A non veteran can assume a VA loan if they qualify with the loan servicer, but the seller's VA entitlement stays tied to the loan until it's paid off.
What is the funding fee on a VA loan assumption?
The VA funding fee on an assumption is 0.5% of the loan balance, and it's waived for veterans receiving VA disability compensation.
Do VA assumable loans require a down payment?
Not in the traditional sense, but the buyer needs to cover the gap between the loan balance and the price, with cash or sometimes a second loan.
How long does a VA loan assumption take?
Often 45 to 90 days or more, depending on the loan servicer. Plan your contract timeline around it.
What is entitlement substitution?
If the buyer is a VA eligible veteran, they can substitute their entitlement for the seller's, which restores the seller's entitlement so they can use it again.
How do I find VA assumable homes in Portland?
Start with the Portland VA assumable home search on this page, then contact me to research whether a specific home's loan is assumable.
More Guides for Veterans
Meet Your Veteran Realtor
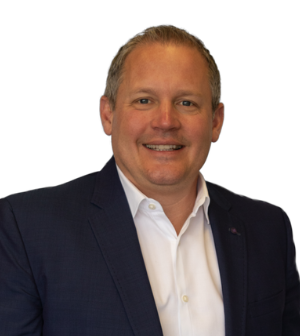
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call, text, or email? 503.997.4169 · Text Us · troy@nwrealtysource.com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. This page is general information, not legal, tax, or lending advice.