Buyer Resource Center › Choosing the Right Representation › ABR® Buyer's Agent
When you buy a home with a VA loan, the agent you choose matters. A VA purchase has its own appraisal, its own contract language, and its own rules about who pays what, and the wrong agent can cost you a home or thousands of dollars. As a Marine Corps veteran and Accredited Buyer's Representative (ABR®), I make sure veterans and military families across the Portland metro and SW Washington get an agent who's working only for them.
What the ABR® Designation Means
The Accredited Buyer's Representative designation is awarded by the National Association of REALTORS® to agents who go beyond the basics of buyer representation.
Training Focused on Buyers
The ABR® requires advanced coursework built entirely around representing buyers, from search strategy to negotiation and closing.
Proven Buyer Experience
To earn it, an agent must also document real transactions where they represented the buyer. It's training backed by practice, not just a class.
Loyalty to You
An ABR® agent's job is to protect your interests, your money, and your timeline. The listing agent works for the seller. I work for you.
6 Ways an ABR® Agent Helps Veteran Buyers
Making Your VA Offer Competitive
Some sellers and listing agents still believe VA offers are slower, pickier, or riskier than conventional ones. Most of that is outdated. A well prepared VA offer with a strong pre-approval, a realistic timeline, and clear terms can compete with anyone.
Navigating the VA Appraisal
Every VA loan requires a VA appraisal, which checks both value and the VA's minimum property requirements. If something comes up, like peeling paint on an older home or a missing handrail, it may need to be fixed before closing.
Protecting You If the Appraisal Comes in Low
Every VA purchase contract includes the VA amendatory clause. If the home appraises below your price, you aren't required to buy it or lose your earnest money. From there we can renegotiate the price, ask for a reconsideration of value, cover part of the gap, or walk away.
Negotiating Seller Concessions
VA loans let sellers pay your normal closing costs, plus additional concessions up to 4 percent of the home's value for things like prepaid taxes and insurance or paying off certain debts. Knowing how to ask, and how much, can save you thousands of dollars.
Inspections and Repairs Done Right
The VA appraisal isn't a home inspection. I recommend a full inspection, and a sewer scope for older Portland homes, then help you decide which repairs to request, which to take a credit for, and which aren't worth fighting over.
Local Knowledge for Military Moves
From Hillsboro and Beaverton to Vancouver and Camas, every part of the Portland metro and SW Washington has its own pricing, commute, schools, and quirks. If you're PCSing in, you may be buying from out of state on a tight timeline.
What Working With Me Looks Like
Every buyer is different, but here's the path most of my veteran clients follow from our first call to closing day.
Free Consultation
We talk through your goals, timeline, BAH or budget, and the areas you're considering.
VA Pre-Approval
I connect you with VA experienced lenders so you know your numbers and your offer is strong.
Home Search
Tours in person or by video, with honest feedback on every home's value and condition.
Offer and Negotiation
A VA savvy offer that protects your earnest money and your bottom line.
Inspection and Appraisal
We handle repairs, VA requirements, and any appraisal issues together.
Closing Day
Final walkthrough, signing, and keys in your hand. Welcome home.
The bottom line: Your VA loan is one of the best benefits you earned. Pair it with an agent who knows how to use it, negotiates for you, and understands military life firsthand, and you'll buy with a lot more confidence and a lot less stress.
Frequently Asked Questions
What is an Accredited Buyer's Representative (ABR®)?
The ABR® is a designation of the National Association of REALTORS®, conferred by the Center for REALTOR® Development. Agents earn it by completing advanced training in buyer representation and documenting real transactions where they represented buyers.
Why should a veteran work with an ABR® agent?
VA loans come with their own appraisal process, contract language, and rules about closing costs. An ABR® agent who also understands VA loans and military moves can make your offer more competitive, protect your earnest money, and negotiate costs on your behalf.
Are VA offers weaker than conventional offers?
Not when they're prepared well. Many concerns about VA loans are outdated. With a solid pre-approval, a realistic timeline, and an agent who explains the VA process to the listing agent, a VA offer can compete with conventional buyers.
What happens if the VA appraisal comes in low?
The VA amendatory clause in your contract means you aren't required to buy the home or lose your earnest money if it appraises below the price. You can renegotiate the price, request a reconsideration of value, pay the difference in cash, or walk away.
Can the seller pay my closing costs on a VA loan?
Yes. Sellers can pay your normal closing costs, plus concessions of up to 4 percent of the home's value for items like prepaid taxes and insurance. How much you can ask for depends on the market and the home, and that's where negotiation matters.
How is a buyer's agent paid?
Compensation is negotiable and isn't set by law. It's spelled out in a written buyer agreement before we tour homes, and in many cases the seller agrees to cover some or all of it. We'll review your options together, including how they work with your VA loan.
Meet Your Veteran Realtor
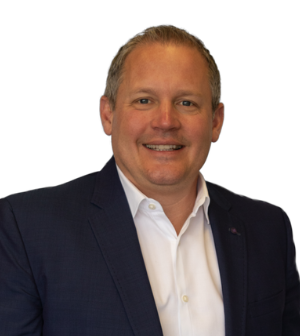
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call or email? 503.997.4169 · troy@nwrealtysource.com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. Content adapted in part from ABR® consumer resources. This page is general information, not legal, tax, or lending advice.