Buyer Resource Center › The Home Search › 8 Expensive Homebuyer Mistakes
Whether this is your first home or you're coming back to the market after a few years, a handful of avoidable mistakes can cost buyers thousands. Here are the eight I see most often around Portland and SW Washington, along with a few tips specifically for veterans and military families.
The 8 Mistakes to Avoid
Borrowing Too Much Money
Just because a lender approves you for a big number doesn't mean you should spend it. The smartest buyers I work with pick a monthly payment they're comfortable with first, then shop in that price range. Leave room in the budget for property taxes, insurance, utilities, and the surprises every house throws at you.
Not Checking Your Credit Report
Pull your credit reports before you talk to a lender and look for errors, old accounts that should be closed, or balances reported wrong. Fixing mistakes early can raise your score and lower your rate, and even a small rate difference adds up to thousands over the life of a loan.
Overlooking Homebuyer Assistance Programs
There are programs at the local, state, and national level that can lower your down payment or help with closing costs. A lot of buyers never ask about them and leave real money on the table.
Creating Red Flags During Underwriting
Your lender will recheck your finances right before closing. Changing jobs, financing a new truck, opening a credit card for furniture, or moving large sums between accounts can delay your loan or even sink it. Keep everything steady until you have the keys.
Skipping the Home Inspection
A home inspection usually costs a few hundred dollars and can save you from a five figure surprise like a failing roof, an old sewer line, or a tired furnace. Always write an inspection contingency into your offer so you have time to review the findings and negotiate.
Not Comparing Lenders and Mortgage Products
Rates, fees, and service can vary a lot from one lender to the next. Get a couple of quotes, compare the Loan Estimates side by side, and ask how quickly they typically close. A responsive lender can make or break a tight timeline.
Buying Through the Seller's Agent
It can feel natural to call the agent on the sign, but the listing agent's job is to get the best result for the seller. You deserve someone whose loyalty is to you, who will tell you when a house is overpriced and negotiate on your behalf.
Not Choosing a Qualified Buyer's Agent
Experience matters. One of the best ways to protect your finances is to work with an agent who has earned the Accredited Buyer's Representative (ABR®) designation, which means extra training focused entirely on representing buyers.
The bottom line: Most of these mistakes come down to rushing or going it alone. Get your finances in order early, ask about every program you might qualify for, and surround yourself with a lender and a buyer's agent who know the VA process. That's how you end up in a home you love at a price that works.
Frequently Asked Questions
Does a VA loan require a home inspection?
No, the VA doesn't require one, but I strongly recommend it. The VA appraisal checks the home's value and the VA's minimum property requirements. It isn't a full inspection, and the appraiser won't check things like the sewer line, attic, or crawl space. A general inspection, plus a sewer scope for older Portland homes, is money well spent.
How much house can I afford with a VA loan?
Your lender looks at your debt to income ratio and the VA's residual income guideline, which measures what's left each month after your bills. That gives you a maximum, but the better number is the monthly payment you're comfortable with, including property taxes, insurance, and upkeep. Start there and shop in that range.
Is there a minimum credit score for a VA loan?
The VA doesn't set a minimum credit score, but most lenders set their own, and a higher score usually gets you a better rate. Check your credit reports for errors before you apply so there are no surprises.
Do disabled veterans have to pay the VA funding fee?
Veterans who receive VA compensation for a service connected disability are generally exempt from the VA funding fee. A few other groups are exempt too, such as surviving spouses who receive Dependency and Indemnity Compensation. Your lender can confirm your status from your Certificate of Eligibility.
Can I buy a home using the listing agent?
You can, but the listing agent's job is to represent the seller. In some cases one agent can represent both sides with written consent, but then neither side gets full advocacy on price and terms. Having your own buyer's agent means someone is negotiating only for you.
Should I change jobs or buy a car before closing?
It's best to wait. Lenders recheck your finances right before closing, and a new job, new loan, new credit card, or large money transfer can delay or derail your approval. If something is unavoidable, like PCS orders or a separation date, tell your lender right away so they can plan around it.
Keep Reading
3 Homebuyer Tips on Credit Scores and Inquiries
Protect your score while you shop for a VA or conventional loan.
Read more ›The Home Inspection Process
What an inspector checks, how to get the most from your inspection, and how VA appraisals differ.
Read more ›Why Veterans Hire an ABR® Buyer's Agent
How an Accredited Buyer's Representative helps you win with a VA offer and protects your interests.
Read more ›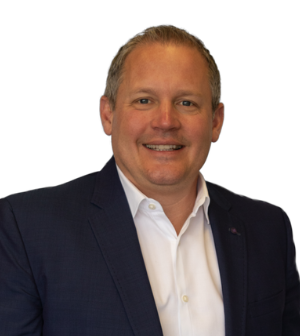
Meet Your Veteran Realtor
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call or email? 503.997.4169 · troy@nwrealtysource.com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. Content adapted in part from ABR® consumer resources. This page is general information, not legal, tax, or lending advice.