Buyer Resource Center › The Home Buying Process › Understand the Differences Between Mortgage Providers
The VA doesn't lend money directly for most home purchases. It guarantees loans made by private lenders, which means the lender you choose has a big impact on your rate, your fees, and how smoothly your purchase goes. Here's how the main types of mortgage providers compare, and what to look for as a veteran buyer.
5 Types of Mortgage Providers
Banks
Large national and regional banks offer a full range of loan programs and may give you a relationship discount if you already bank with them. Service can vary, and some banks are slower or less flexible on unusual situations.
Credit Unions
Credit unions are member owned and sometimes offer competitive rates and lower fees. Several credit unions focus specifically on military members and their families.
Mortgage Brokers
A broker doesn't lend money directly. Instead, they shop your loan to multiple wholesale lenders to find a good fit, which can help if your situation is a little more complex.
Online Lenders
Online lenders can be fast and convenient, with digital applications and quick quotes. The tradeoff can be less personal service and less local knowledge when something unexpected comes up.
VA Specialist Lenders
Some lenders and loan officers focus heavily on VA loans. They tend to know the appraisal process, the funding fee rules, entitlement questions, and assumable loans inside and out.
Questions to Ask Any Lender
How many VA loans do you close?
Experience with VA loans prevents surprises with the appraisal and closing timeline.
What's my rate and APR?
The APR includes fees, which makes it easier to compare lenders side by side.
What are your lender fees?
Compare origination, underwriting, and processing fees on each Loan Estimate.
How fast can you close?
Ask about typical VA closing times and how they communicate along the way.
Am I exempt from the funding fee?
Veterans with a service connected disability rating generally are. Confirm it early.
Will you count rental income?
Important if you're considering a duplex, triplex, or fourplex.
For Veteran Investors
Thinking About a Duplex, Triplex, or Fourplex?
Your VA loan can buy a building with up to four units with no down payment, as long as you live in one of them. Rent from the other units helps cover the mortgage, and it's one of the best wealth building moves a veteran can make. As a Certified Investor Agent Specialist (CIAS™), I help you run the numbers before you ever write an offer.
Buying a Duplex With a VA Loan Free Investment CalculatorThe bottom line: The right lender can save you money and keep your purchase on track. Get Loan Estimates from two or three lenders within a short window, compare rates, fees, and VA experience, and choose the one you trust to communicate well. I'm happy to help you compare them.
Frequently Asked Questions
Does the VA lend money directly?
Not for most home purchases. The VA guarantees part of the loan, and private lenders like banks, credit unions, and mortgage companies make the actual loan.
Do all lenders offer the same VA loan rates?
No. Rates and fees vary from lender to lender, even on the same day. Comparing Loan Estimates from a few lenders is the best way to find a good deal.
Is a mortgage broker better than a bank?
Not necessarily. A broker can shop multiple lenders for you, while a bank lends its own money. The best choice depends on your situation, the specific loan officer, and their VA experience.
How many lenders should I talk to?
Two or three is usually enough to compare. Try to get all your quotes within about two weeks to limit the effect on your credit score.
What is a Loan Estimate?
It's a standard three page form lenders must give you within three business days of your application. It shows your rate, monthly payment, and closing costs, which makes comparing lenders easier.
Can my agent recommend a VA lender?
Yes. A good agent knows which local lenders communicate well and close on time. You're always free to choose any lender you like.
Keep Reading
3 Homebuyer Tips on Credit Scores and Inquiries
Protect your score while you shop for a VA or conventional loan.
Read more ›15 Ways to Save Money for a Down Payment
Even with a zero down VA loan, cash for closing costs and reserves helps.
Read more ›From Contract to Closing
What happens between an accepted offer and getting your keys.
Read more ›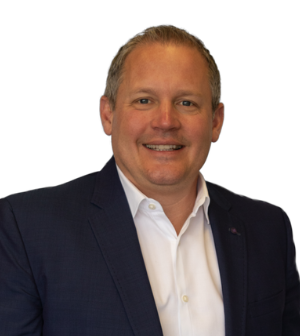
Meet Your Veteran Realtor
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call or email? 503.997.4169 · troy@nwrealtysource.com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. Content adapted in part from ABR® consumer resources. This page is general information, not legal, tax, or lending advice.