Home › Veteran Loans › VA Funding Fee and Closing Costs
VA Funding Fee and Closing Costs: What It Is and Who's Exempt
2026 Funding Fee Rates, Exemptions, and Closing Costs in Portland & SW Washington
Schedule a Free Call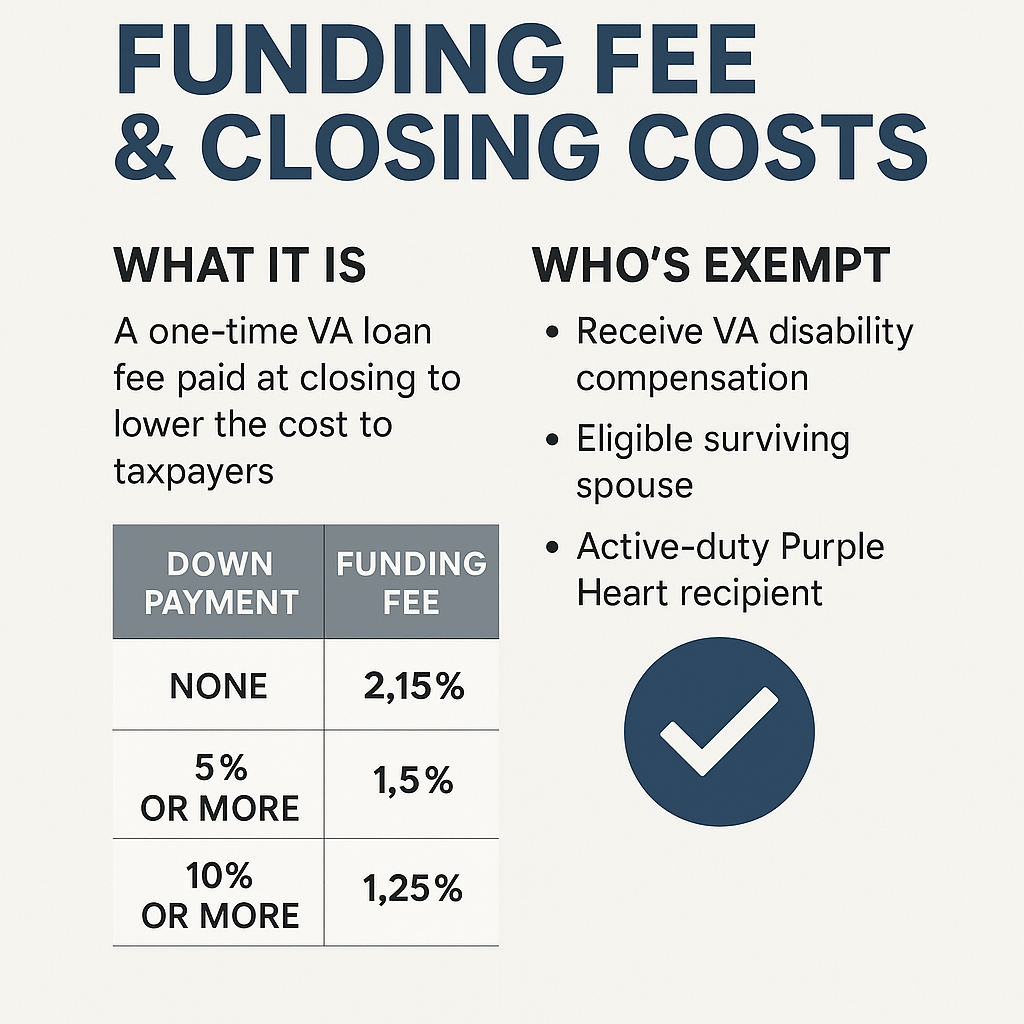
The VA funding fee is a one time charge most veterans and service members pay when they use a VA home loan. It keeps the program running with no ongoing cost to taxpayers, and it's the reason VA loans don't need monthly mortgage insurance. Many veterans don't pay it at all. Here's how much it is, who's exempt, and what to expect for closing costs in the Portland area.
Please note: Portland Veteran Homes is a private, veteran owned real estate company and is not affiliated with the U.S. Department of Veterans Affairs. The rates below come from VA.gov and were checked in November 2026. Your lender's Loan Estimate will show your exact costs.
Funding Fee for Buying or Building a Home
For a VA purchase or construction loan, the fee depends on your down payment and whether you've used your VA benefit before. It's a percentage of the loan amount, not the price.
| Down payment | First use | After first use |
|---|---|---|
| Less than 5% | 2.15% | 3.3% |
| 5% to less than 10% | 1.5% | 1.5% |
| 10% or more | 1.25% | 1.25% |
If your only prior VA loan was for a manufactured home, it still counts as first use.
Funding Fee for Other VA Loans
| Loan type | Funding fee |
|---|---|
| Cash out refinance, first use | 2.15% |
| Cash out refinance, after first use | 3.3% |
| IRRRL streamline refinance | 0.5% |
| Loan assumption | 0.5% |
| Manufactured home not on a permanent foundation | 1% |
| Native American Direct Loan, purchase | 1.25% |
| Native American Direct Loan, refinance | 0.5% |
| Vendee loan (buying a VA owned home) | 2.25% |
Refinancing to a lower rate? See how the VA IRRRL streamline refinance works.
What It Looks Like in Dollars
| $550,000 purchase, $0 down | Funding fee | Loan amount |
|---|---|---|
| First use (2.15%) | $11,825 | $561,825 if financed |
| After first use (3.3%) | $18,150 | $568,150 if financed |
| With 5% down (1.5% of $522,500) | $7,838 | $530,338 if financed |
| Exempt veteran | $0 | $550,000 |
You can pay the fee at closing, roll it into your loan, or ask the seller to pay it as part of your concessions. It's the only cost you're allowed to finance into a VA purchase loan.
Who's Exempt From the Funding Fee
You don't pay the funding fee if any of these apply:
- You receive VA compensation for a service connected disability.
- You're eligible for disability compensation but receive retirement or active duty pay instead.
- You're a surviving spouse receiving Dependency and Indemnity Compensation (DIC).
- You're a service member with a proposed or memorandum rating, issued before closing, that says you're eligible for compensation based on a pre-discharge claim.
- You're on active duty and provide proof of a Purple Heart on or before closing.
If you're exempt, your Certificate of Eligibility will show it, and the fee won't be charged.
Waiting on a disability claim? If the VA later awards you compensation with an effective date before your closing, you may be able to get the funding fee refunded. A proposed or memorandum rating issued after closing doesn't qualify. Call your VA regional loan center to check, and keep your closing paperwork.
VA Closing Costs
Beyond the funding fee, you'll have normal closing costs. The VA limits what lenders can charge veterans: the lender can charge either a flat fee of up to 1% of the loan or certain itemized fees, plus any discount points you choose to lower your rate. Closing costs, including prepaid taxes and insurance, often run about 2% to 5% of the price, depending on the home and your loan.
| Cost | What it is | Who usually pays in Oregon and SW Washington |
|---|---|---|
| Lender charges | Either a flat fee of up to 1% of the loan or certain itemized fees, plus any discount points you choose | Buyer (negotiable) |
| VA appraisal | Set by the VA and paid to a VA assigned appraiser | Buyer (negotiable) |
| Credit report | Pulled by the lender | Buyer |
| Lender's title policy | Protects the lender | Buyer |
| Owner's title policy | Protects you | Seller, by local custom |
| Escrow fee | The neutral company that handles closing | Usually split between buyer and seller |
| Recording fees | Recording the deed and deed of trust | Buyer and seller each pay their own |
| Prepaid items | Property taxes, homeowners insurance, and interest to start your escrow account | Buyer (seller concessions can cover them) |
| Transfer or excise taxes | Washington's real estate excise tax and Washington County, OR's transfer tax | Seller, by custom |
Who pays what is negotiable and local customs vary, so your agent and escrow officer will confirm the details for your sale.
How Sellers Can Help
With a VA loan, the seller can pay all of your normal closing costs, and there's no VA limit on those credits. On top of that, the seller can give you up to 4% of the home's reasonable value, as shown on the VA Notice of Value, in concessions. Concessions can cover:
- Your VA funding fee
- Prepaid property taxes and homeowners insurance
- Paying off debts or collections to help you qualify
- Other items your lender allows
On a $550,000 home, that's up to $22,000 in concessions, plus your normal closing costs. In today's more balanced Portland market, sellers are often open to it, and many of my veteran clients move in with very little cash out of pocket.
Ways to Lower Your Costs
Ask for Seller Concessions
Request that the seller pay your closing costs and funding fee in your offer.
Check Your Exemption
If you have or expect a disability rating, make sure it shows on your COE before closing.
Put Down 5% or More
Even 5% down drops the funding fee to 1.5%, or 1.25% at 10% down.
Compare Lenders
Get Loan Estimates from at least two VA lenders on the same day and compare fees and rates.
Oregon veteran with 5% or more to put down? ODVA's state loan has no funding fee. Compare it in ODVA vs. Federal VA Loan.
Related Guides
Do Veterans Get Cheaper Home Loans?
How VA loans compare to conventional loans.
VA Home Loan Guide
Loan limits, entitlement, and the full process.
VA Financing Guide
70 mortgage questions answered for veterans.
VA Home Loans: Getting Started
The VA lending team I trust.
Ready to Start Your Home Search?
Browse homes in the Portland metro and across the river in Vancouver, Camas, and Ridgefield.
Frequently Asked Questions
How much is the VA funding fee in 2026?
For a purchase, it's 2.15% of the loan the first time you use your VA benefit and 3.3% after that with less than 5% down. It's 1.5% with 5% to 10% down and 1.25% with 10% or more down. The IRRRL and assumption fees are 0.5%.
Who is exempt from the VA funding fee?
Veterans receiving VA compensation for a service connected disability, veterans eligible for compensation but receiving retirement or active duty pay instead, surviving spouses receiving DIC, service members with a pre-discharge rating issued before closing, and active duty Purple Heart recipients.
Can I roll the funding fee into my loan?
Yes. The funding fee is the only cost you can finance into a VA purchase loan. You can also pay it at closing or have the seller pay it as a concession.
Can I get a refund of the VA funding fee?
Possibly. If the VA later awards you disability compensation with an effective date before your closing, you may qualify for a refund. Contact your VA regional loan center.
How much can a seller pay toward a VA buyer's costs?
The seller can pay all of your normal closing costs, plus up to 4% of the home's reasonable value in concessions, which can cover the funding fee, prepaid items, or paying off debts.
What closing costs can a VA lender charge?
A VA lender can charge either a flat fee of up to 1% of the loan or certain itemized fees, plus any discount points you choose. Other costs include the appraisal, title, escrow, recording, and prepaid taxes and insurance.
How much are closing costs on a VA loan?
Closing costs, including prepaid taxes and insurance, often run about 2% to 5% of the price. Seller concessions can cover much or all of them.
More Guides for Veteran Buyers
Meet Your Veteran Realtor
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call or email? 503.997.4169 · troy@nwrealtysource.com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. This page is general information, not legal, tax, or lending advice.