Home › Veteran Loans › VA IRRRL Streamline Refinance
VA IRRRL Streamline Refinance: How It Works
Lower Your Rate on an Existing VA Loan With Less Paperwork

If you already have a VA loan and rates have dropped since you bought, the VA's Interest Rate Reduction Refinance Loan, or IRRRL, is usually the fastest and cheapest way to lower your payment. It's often called the VA streamline refinance because it skips much of the paperwork a normal refinance requires. Here's how it works, the current rules, and how to tell whether it's worth it.
Please note: Portland Veteran Homes is a private, veteran-owned real estate company and is not affiliated with the U.S. Department of Veterans Affairs. I'm a real estate broker, not a lender. The rules below were checked against VA.gov and current VA guidance in November 2026. Your lender will confirm what applies to your loan.
What Is a VA IRRRL?
An IRRRL replaces your current VA loan with a new VA loan at a lower rate, or moves you from an adjustable rate to a stable fixed rate. The VA created it so veterans can take advantage of better rates without a long, expensive refinance. You don't need a new Certificate of Eligibility, and the VA doesn't require an appraisal or income verification, although many lenders still check credit and income.
Key Benefits
Lower Monthly Payment
A lower rate means a lower payment, often by hundreds of dollars a month.
Less Paperwork
The VA doesn't require an appraisal or full income documentation, so IRRRLs often close in a few weeks.
Low Funding Fee
The funding fee is just 0.5% of the loan, and it's waived if you receive VA disability compensation.
Little or No Cash at Closing
You can roll closing costs and the funding fee into the new loan, or take a slightly higher rate so the lender covers them.
Works on a Rental
You only need to certify that you lived in the home at some point, so an IRRRL can work even after a PCS move.
Switch ARM to Fixed
Lock in a fixed rate and stop worrying about future adjustments on an adjustable loan.
Current IRRRL Rules
Federal law added protections in 2018 to make sure every IRRRL actually helps the veteran. Here's what must be true:
| Requirement | What it means |
|---|---|
| Existing VA loan | You must be refinancing a VA backed loan into a new VA backed loan |
| Occupancy | You must certify that you live in the home now or lived there before. It can be a rental today |
| Seasoning | At least 210 days since your first payment and at least six monthly payments made, whichever is later |
| Rate reduction | Fixed to fixed: at least 0.5% lower. Fixed to adjustable: at least 2% lower. Adjustable to fixed: no minimum |
| 36 month recoupment | Your monthly savings must cover the refinance closing costs within 36 months |
| Payment history | Most lenders want no late mortgage payments in the past 12 months |
| Second mortgage | Any second lien holder must agree to stay in second position |
Lenders may add their own requirements, such as a minimum credit score, so compare more than one. Full details are on the VA's IRRRL page.
Is It Worth It? Run the Break Even
The simple test: divide your closing costs by your monthly savings. That's how many months it takes to come out ahead. If you'll keep the home longer than that, the refinance likely makes sense. Here's an example.
| $400,000 balance, new 30 year loan | Current Loan | After IRRRL |
|---|---|---|
| Interest rate | 7.00% | 6.25% |
| Loan amount | $400,000 | $402,000 (0.5% funding fee rolled in) |
| Principal and interest | $2,661 | $2,475 |
That's about $186 a month in savings. With $4,000 in closing costs, you'd recoup them in about 22 months, well inside the VA's 36 month limit, and come out ahead every month after that.
This is an illustration only. Your savings depend on your balance, rates, and costs. Starting a new 30 year loan can also add years of payments, so ask your lender about a shorter term if you want to stay on track to pay off your home.
How the Process Works
Check Your Numbers
Find your current rate, balance, and first payment date on your mortgage statement. Make sure you've passed 210 days and six payments.
Compare Lenders
You don't have to use your current lender. Get Loan Estimates from two or three VA lenders and compare the rate, fees, and break even.
Apply and Lock
Provide your mortgage statement, ID, and homeowners insurance. Your lender may also check credit. Lock your rate once you're happy with it.
Close and Start Saving
Your new VA loan pays off the old one. Because of how mortgage interest works, you'll usually skip a payment month at closing.
What an IRRRL Doesn't Do
- It doesn't give you cash out. For that, you'd use a VA cash out refinance.
- It isn't for debt consolidation.
- It only replaces an existing VA loan with a new VA loan.
IRRRL vs. VA Cash Out Refinance
| VA IRRRL | VA Cash Out Refinance | |
|---|---|---|
| Purpose | Lower your rate or move from an ARM to a fixed rate | Take cash out, or refinance any loan type into a VA loan |
| Current loan | Must be a VA loan | Any loan type (VA, FHA, conventional) |
| Cash to you | No | Yes, up to 100% of value per VA rules (lenders often cap at 90%) |
| Appraisal | Usually not required by the VA | Required |
| Income and credit review | Limited. The VA doesn't require it, but many lenders check | Full underwriting |
| Funding fee | 0.5% | 2.15% first use, 3.3% after |
| Occupancy | Lived there now or before | Must live there now |
Thinking about selling instead? If your VA loan has a low rate, it may be assumable, which can help your home stand out to buyers. See my Veteran Seller Advantage Program or find out what your home is worth.
The Bottom Line
If you're a veteran, service member, or surviving spouse with a VA loan and today's rates are at least half a point lower than yours, the IRRRL is one of the simplest ways to cut your payment. I work with VA lenders who can run your numbers in minutes, and I'm happy to connect you. Call or text me at 503.997.4169.
Related Guides
VA Funding Fee and Closing Costs
What the funding fee is and who's exempt.
Do Veterans Get Cheaper Home Loans?
How VA loans compare to conventional loans.
VA Financing Guide
70 mortgage questions answered for veterans.
VA Home Loans: Getting Started
The VA lending team I trust.
Ready to Start Your Home Search?
Browse homes in the Portland metro and across the river in Vancouver, Camas, and Ridgefield.
Frequently Asked Questions
What is a VA IRRRL?
An Interest Rate Reduction Refinance Loan replaces your current VA loan with a new VA loan at a lower rate, or moves you from an adjustable rate to a fixed rate. It's often called the VA streamline refinance.
How soon can I do a VA IRRRL?
At least 210 days must pass after your first payment on the current loan, and you must have made at least six monthly payments, whichever is later.
How much lower does my rate need to be?
Going from a fixed rate to a new fixed rate, the new rate must be at least 0.5% lower. Going from fixed to adjustable, it must be at least 2% lower. Going from an adjustable to a fixed rate has no minimum.
What is the funding fee on an IRRRL?
It's 0.5% of the loan amount and can be rolled into the new loan. Veterans who receive VA compensation for a service connected disability don't pay it.
Do I need an appraisal or credit check for an IRRRL?
The VA doesn't require an appraisal or income verification for an IRRRL, but many lenders still check credit and some order an appraisal. Ask each lender about its requirements.
Can I do an IRRRL on a home I no longer live in?
Yes. You only need to certify that you lived in the home at some point. That makes the IRRRL useful for veterans who moved and kept the home as a rental.
Can I take cash out with an IRRRL?
No. An IRRRL is only for lowering your rate or moving to a fixed rate. To take cash out, you'd use a VA cash out refinance, which requires an appraisal and full underwriting.
Do I have to use my current lender?
No. Any VA lender can do your IRRRL, so it's worth comparing Loan Estimates from a few lenders.
More Guides for Veterans
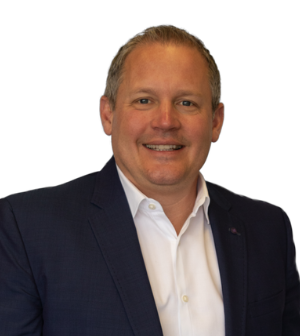
Meet Your Veteran Realtor
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call, text, or email? 503.997.4169 · Text Us · troy [at] nwrealtysource [dot] com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP®, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. This page is general information, not legal, tax, or lending advice.