Home › Articles and News › Understanding VA Loans
Understanding VA Loans: Your Earned Benefit
How the VA home loan works and why it's one of the strongest ways to buy
The VA home loan is one of the most valuable benefits you earned through your service. Here's a quick look at where it came from, how it works, and why it's still the best way for most veterans to buy a home in the Portland metro and SW Washington.
A Benefit With an 80 Year History
The VA home loan began in 1944 as part of the Servicemen's Readjustment Act, better known as the GI Bill. It was created to help returning World War II veterans buy homes. Since then, the VA has guaranteed more than 29 million home loans.
How a VA Loan Works
The VA doesn't lend the money. It guarantees part of the loan, which protects the lender and lets them offer better terms. That guarantee is why VA loans offer:
$0 Down
With full entitlement, there's no down payment and no VA loan limit at any price your lender approves.
No PMI
VA loans never require monthly private mortgage insurance.
Flexible Credit
The VA doesn't set a minimum credit score. Most lenders look for 580 to 620.
A Reusable Benefit
Your VA benefit never expires and can be used again after a prior VA loan is paid off.
 Watch the VideoVA Home Loan Benefits for Portland Metro VeteransNo down payment is just the start.
The VA Funding Fee
Instead of monthly mortgage insurance, most buyers pay a one time funding fee that can be rolled into the loan.
| Down Payment | First Use | Subsequent Use |
|---|---|---|
| Less than 5% | 2.15% | 3.30% |
| 5% to 9.99% | 1.50% | 1.50% |
| 10% or more | 1.25% | 1.25% |
Veterans receiving VA disability compensation, active duty Purple Heart recipients, and surviving spouses receiving Dependency and Indemnity Compensation don't pay the funding fee.
Who Is Eligible
Veterans, active duty service members, qualifying National Guard and Reserve members, and certain surviving spouses may be eligible. Your discharge must be under conditions other than dishonorable. See my VA Loan Requirements Checklist for the service requirements, and my Complete VA Home Loan Guide for loan limits and the step by step buying process.
Ready to Start Your Home Search?
Browse homes in the Portland metro and across the river in Vancouver, Camas, and Ridgefield.
Frequently Asked Questions
When did the VA home loan program start?
In 1944, as part of the Servicemen's Readjustment Act, better known as the GI Bill. It has helped veterans buy homes for more than 80 years.
How many VA loans have been guaranteed?
More than 29 million since 1944.
How much is the VA funding fee?
For a first time VA purchase with less than 5% down, it's 2.15% of the loan amount. It's 3.3% for later uses with less than 5% down, and it drops to 1.5% or 1.25% with a larger down payment. Veterans receiving VA disability compensation don't pay it.
Who is eligible for a VA loan?
Veterans, active duty service members, National Guard and Reserve members who meet the service requirements, and certain surviving spouses. A dishonorable discharge makes you ineligible.
More Guides for Veterans
Meet Your Veteran Realtor
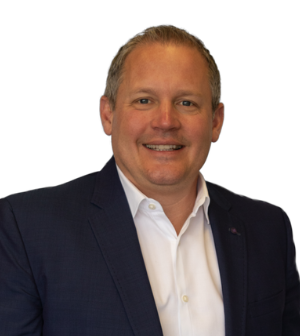
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call, text, or email? 503.997.4169 · Text Us · troy [at] nwrealtysource [dot] com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP®, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. This page is general information, not legal, tax, or lending advice.