Buyer Resource Center › The Home Buying Process › 15 Ways to Save Money for a Down Payment
If you're using a VA loan, you may not need a down payment at all. But buying a home still takes some cash, and having a cushion makes the whole process less stressful. Whether you're saving for closing costs, a down payment on a conventional loan, or money in the bank after you move in, these 15 ideas will help you get there faster.
What You'll Still Want Cash For
Earnest Money and Inspections
Your earnest money deposit shows the seller you're serious and goes toward your closing costs. You'll also pay for your home inspection and any specialty inspections up front.
Closing Costs
Lender fees, title insurance, escrow fees, prepaid taxes, and insurance add up. On a VA loan, the funding fee can be rolled into your loan, and sellers can contribute toward your costs.
Reserves and Move In Costs
It's smart to keep some savings after closing for repairs, furniture, and the surprises every home brings. Some lenders also require reserves, especially on multi unit properties.
15 Ways to Save
Pick a few that fit your life and start this week. Small, steady changes add up faster than you think.
Set a clear goal
Ask a VA lender to estimate your closing costs, earnest money, and reserves so you know your exact target.
Automate it
Send a set amount to a separate savings account every payday before you can spend it.
Use a high yield account
Keep your house fund in a high yield savings account so it earns more while it grows.
Trim subscriptions
Cancel streaming, apps, and memberships you don't use and redirect the savings.
Cut back on eating out
Cooking at home a few more nights a week adds up fast.
Pay down high interest debt
Lower balances improve your debt to income ratio and free up cash each month.
Save windfalls
Put tax refunds, bonuses, and reenlistment bonuses straight into your house fund.
Bank your raises
When your pay goes up, save the difference instead of raising your spending.
Pick up extra income
Overtime, a side gig, or selling things you no longer need can speed things up.
Sell before you move
Downsizing before a PCS or move cuts moving costs and puts cash in your pocket.
Ask about gift funds
Family can gift money toward your purchase, with a simple gift letter for your lender.
Look into assistance programs
Oregon and Washington both have down payment and closing cost assistance programs for qualifying buyers.
Negotiate seller concessions
On a VA loan, sellers can pay your normal closing costs plus additional concessions up to 4 percent of value.
Compare lender credits
Some lenders offer credits toward closing costs in exchange for a slightly higher rate.
Use the Savings Deposit Program
Service members deployed to qualifying areas can earn 10 percent annual interest through the military's Savings Deposit Program.
For Veteran Investors
Thinking About a Duplex, Triplex, or Fourplex?
Your VA loan can buy a building with up to four units with no down payment, as long as you live in one of them. Rent from the other units helps cover the mortgage, and it's one of the best wealth building moves a veteran can make. As a Certified Investor Agent Specialist (CIAS™), I help you run the numbers before you ever write an offer.
Buying a Duplex With a VA Loan Free Investment CalculatorThe bottom line: With a VA loan, you may need far less cash than you think to buy a home. Set a clear target, automate your savings, and use the military and state programs available to you. When you're getting close, let's talk so you can start your search with confidence.
Frequently Asked Questions
Do I need a down payment for a VA loan?
No. Eligible veterans and service members can buy with no down payment, as long as the price doesn't exceed the appraised value. You'll still want cash for earnest money, inspections, and reserves.
How much cash should I have to buy a home with a VA loan?
It varies, but plan for earnest money, inspections, any closing costs the seller doesn't cover, and a cushion for after you move in. A VA lender can give you an estimate based on your price range.
Can the seller pay my closing costs?
Yes. On a VA loan, sellers can pay your normal closing costs, plus additional concessions of up to 4 percent of the home's value.
Can family help with my down payment or closing costs?
Yes. Gift funds from family are allowed. Your lender will ask for a gift letter and documentation showing where the money came from.
Are there down payment assistance programs in Oregon and Washington?
Yes. Both states, along with some cities and counties, offer down payment or closing cost assistance for qualifying buyers. Income limits and rules vary, so ask your lender which programs fit your situation.
What is the military Savings Deposit Program?
It's a Department of Defense program that lets service members deployed to qualifying areas deposit money and earn 10 percent annual interest. It can be a powerful way to build savings for a home.
Keep Reading
3 Homebuyer Tips on Credit Scores and Inquiries
Protect your score while you shop for a VA or conventional loan.
Read more ›Understand the Differences Between Mortgage Providers
Banks, credit unions, brokers, and VA specialists compared.
Read more ›5 First Time Homebuyer Tips
Smart first steps for veterans buying their very first home.
Read more ›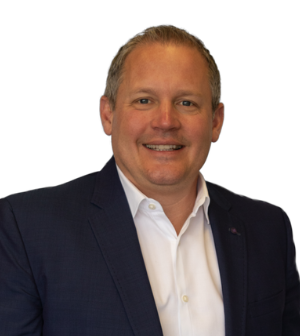
Meet Your Veteran Realtor
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call or email? 503.997.4169 · troy@nwrealtysource.com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. Content adapted in part from ABR® consumer resources. This page is general information, not legal, tax, or lending advice.