Home › Blog › Common Questions Veteran Home Buyers Ask
Common Questions Veteran Home Buyers Ask in Portland, OR
Straight Answers on VA Loans, ODVA Loans, and Buying in Portland and SW Washington
Call or Text Us
Buying a home is a big step for anyone, but veterans in Portland have their own set of questions and some real advantages. After 25 years and more than 1,000 homes sold, these are the questions I hear most from veteran buyers, with straight answers and no fluff.
Please note: Portland Veteran Homes is a private, veteran owned real estate company. We are not affiliated with the U.S. Department of Veterans Affairs or the Oregon Department of Veterans' Affairs. Program terms below were checked against the VA's and ODVA's official websites in November 2026 and can change, so always confirm with your lender.
1What VA or Oregon Programs Can Help Me Buy a Home?
Veterans buying in Oregon have two separate loan programs, and they work very differently.
- Federal VA Home Loan. Backed by the U.S. Department of Veterans Affairs and made by private lenders. No down payment with full entitlement, no monthly mortgage insurance, limits on what you can be charged at closing, and competitive rates.
- ODVA Home Loan (ORVET). Oregon is one of only a handful of states with its own veteran home loan. ODVA funds and services the loan directly from Salem. It offers fixed rate 15, 20, or 30 year loans for an owner occupied single family home in Oregon, with no minimum credit score, gift funds allowed for the down payment, and financing up to 95% of the price or appraised value.
For most of my clients the federal VA loan wins because it needs no money down. ODVA can make sense when its rate is attractive and you have at least 5% to put down. The comparison table below shows the differences side by side.
VA Loan vs. ODVA Loan at a Glance
| Federal VA Loan | ODVA (ORVET) Loan | |
|---|---|---|
| Who backs it | U.S. Department of Veterans Affairs guarantee; you borrow from a private lender | Oregon Department of Veterans' Affairs funds and services the loan itself, from its Salem office |
| Down payment | None with full entitlement | At least 5%. Maximum loan is 95% of price or appraised value |
| Mortgage insurance | None. A one time VA funding fee instead (waived for many disabled veterans) | PMI required when you borrow more than 80% |
| Loan limit | No limit with full entitlement. $832,750 in the Portland metro with partial entitlement | Up to the Fannie Mae conforming limit ($832,750 in 2026) |
| Minimum credit score | None set by the VA. Most lenders look for about 620 | None set by ODVA. Follows Fannie Mae underwriting |
| Property types | One to four units, condos on the VA list, manufactured homes on land, new construction | Single family only: site built homes, condos, townhomes, manufactured homes on owned land. No multi family |
| Where | Anywhere in the U.S., including SW Washington | Oregon properties only |
| Refinancing | Yes (IRRRL and cash out) | No. Purchase only |
| Times you can use it | Unlimited, as entitlement is restored or available | Up to 4 times in your life, one loan open at a time |
| Eligibility proof | VA Certificate of Eligibility (COE) | Separate ODVA eligibility approval. A COE doesn't count |
Sources: ODVA Home Loan Program, ODVA Home Loan FAQs, and the U.S. Department of Veterans Affairs.
2What Is a Certificate of Eligibility (COE), and What Is Entitlement?
Your Certificate of Eligibility proves to a lender that you qualify for a VA loan. Most lenders can pull it online in minutes. Your entitlement is the amount the VA will guarantee. If you have full entitlement, there's no VA loan limit, so you can buy with zero down at any price your income and credit support.
If part of your entitlement is still tied up in another VA loan, you have partial entitlement, and the 2026 county loan limit of $832,750 in the Portland metro is used to figure out whether you need a down payment.
3Am I Eligible for an ODVA Loan Too?
Maybe, but it's a separate approval. ODVA's rules are different from the federal VA's, and a federal COE does not make you eligible. You must have served on active duty and meet one of ODVA's service criteria, such as:
- More than 178 consecutive days of active duty (90 days if you entered on or before January 31, 1955) with an honorable discharge
- Fewer days if you were discharged for a service connected disability or have a VA disability rating
- At least one day in a combat zone, or a combat, campaign, or expeditionary ribbon or medal, with an honorable discharge
- Currently receiving a nonservice connected VA pension
You don't have to live in Oregon when you apply, but you must move in within 60 days of closing. You can apply on ODVA's eligibility page by upload, fax, or mail.
4Do I Actually Need a Down Payment?
With a federal VA loan and full entitlement, no. Zero down is the whole point.
With an ODVA loan, yes. ODVA lends up to 95% of the price or appraised value, whichever is lower, so plan on at least 5% down. If you put down less than 20%, ODVA requires private mortgage insurance. Gift funds from family can be used for the down payment as long as they're documented and don't have to be paid back.
5What Is the VA Funding Fee, and Do I Have to Pay It?
Instead of monthly mortgage insurance, VA loans have a one time funding fee. It can be paid at closing or rolled into the loan. Here are the current rates for a purchase:
| Down payment | First use | After first use |
|---|---|---|
| Less than 5% | 2.15% | 3.3% |
| 5% to less than 10% | 1.5% | 1.5% |
| 10% or more | 1.25% | 1.25% |
You don't pay the fee at all if you receive VA compensation for a service connected disability, are a surviving spouse receiving DIC, or are an active duty Purple Heart recipient. Details are on the VA's funding fee page.
6What Credit and Job History Do I Need?
The VA doesn't set a minimum credit score, and neither does ODVA. In practice, most VA lenders look for about 620, and some go lower. Lenders usually want to see two years of steady work. If you're self employed, expect to show two years of tax returns. A job change or a short gap doesn't knock you out, especially if you moved into similar work or were in school or the military.
A past bankruptcy or foreclosure isn't automatically a deal breaker either. VA lenders commonly want about two years after a Chapter 7 discharge. ODVA also reviews past foreclosures and short sales case by case, looking at how much time has passed and your credit since.
7How Do Debt to Income and Residual Income Work?
VA lenders look at your debt to income ratio, usually targeting about 41%, but they also look at residual income, which is the money left over each month after your mortgage, debts, and basic living costs. Strong residual income can get a loan approved even when your ratio is higher than 41%. It's one reason VA loans have such a good track record.
8How Do VA Appraisals and Property Requirements Work?
A VA appraiser checks the value and makes sure the home meets the VA's Minimum Property Requirements. The home has to be safe, structurally sound, and sanitary, with working heat, water, and electrical systems and a roof with life left in it. Cosmetic issues like worn carpet or old paint don't matter. If the appraiser calls for repairs, they need to be done before closing, and we negotiate with the seller on who handles them.
In Oregon, a wood destroying insect inspection is no longer required on every VA loan. It's only needed if the appraiser sees signs of active pests or damage.
9Should I Still Get a Home Inspection?
Yes, every time. The appraisal protects the lender. The inspection protects you. A good inspector spends hours looking at the roof, foundation, plumbing, electrical, and heating, and in older Portland homes I also recommend a sewer scope and checking for an old oil tank. A few hundred dollars now can save you thousands later.
10Can the Seller Help Pay My Closing Costs?
Yes. With a VA loan, the seller can pay all of your normal closing costs, plus up to 4% of the price in extra concessions, like paying your funding fee, prepaid taxes and insurance, or paying off a debt to help you qualify. Combined with zero down, many of my veteran clients move in with very little cash out of pocket. I cover the strategy in my VA home loan guide.
The VA also now lets veterans pay a buyer's agent, and in most Portland deals we ask the seller to cover that fee as part of the offer. I'll walk you through the buyer agreement up front so there are no surprises.
11Can I Buy a Duplex, Fourplex, or New Construction?
With a federal VA loan, yes. You can buy up to four units with zero down as long as you live in one of them, and rent from the other units can help you qualify. See buying a duplex with a VA loan. VA loans also work for new construction when the builder and home meet VA and lender standards.
ODVA loans are for single family homes only, so multi family properties aren't eligible with ODVA.
12Can I Buy a Condo or Manufactured Home?
Yes, with some rules. For a VA loan, the condo project must be on the VA's approved list. You can check using my VA approved condo list page. Manufactured homes qualify with both VA and ODVA when they're permanently attached to land you own and taxed as real estate.
13Can I Take Over a Seller's Low Rate VA Loan?
Yes. VA loans are assumable, so you may be able to take over a seller's existing loan, often at a rate far below today's. You'll need to qualify with the loan servicer, and you'll usually need cash or a second loan to cover the gap between the loan balance and the price. If you're a veteran, you can substitute your entitlement so the seller gets theirs back. Browse Portland homes with assumable VA loans.
14Can I Use My VA Loan in SW Washington?
Yes. The federal VA loan works anywhere in the U.S., so it's a great fit for Vancouver, Camas, Battle Ground, Ridgefield, and the rest of Clark County. The ODVA loan only works for homes in Oregon. Washington also has no state income tax, which matters to a lot of military retirees deciding which side of the river to live on.
15Do Veterans Get a Property Tax Break in Oregon?
Some do. If you have a service connected disability rating of 40% or more, Oregon removes a set amount from your home's assessed value, about $32,500 per the Oregon Department of Revenue's 2026 figures, and the amount goes up about 3% each year. A lower amount is available to certain other disabled veterans and to unremarried surviving spouses. You file the claim with your county assessor, generally by April 1. Learn more on the Oregon Department of Revenue exemptions page or in my guide, Understanding Oregon Property Taxes When Buying a Home as a Veteran.
16Can I Use My VA Loan Benefit Again?
Absolutely. Your federal VA benefit is good for life. When you sell and pay off a VA loan, your entitlement is restored and you can use it again. You can even have two VA loans at once if you have enough remaining entitlement, which is common after a PCS move.
ODVA works differently. You can use an ODVA loan up to four times in your life, but only one ODVA loan can be open at a time. ODVA loans are purchase only, so you can't use the program to refinance.
17How Do I Find the Right Lender and Agent?
Not every agent or lender knows VA loans well, and it shows when a VA offer goes up against a conventional one. Here's what to ask.
Ask Your Agent
How many veteran and military buyers have you helped? How do you make a VA offer competitive? How do you handle appraisal repairs?
Ask Your Lender
How many VA loans do you close each year? What's your average closing time? Do you check residual income and entitlement up front?
As a Marine Corps veteran and Principal Broker, I've helped veterans in Portland and SW Washington for 25 years. I can also introduce you to VA lenders I trust. Here's how to get started.
The Bottom Line
Veterans buying in Portland have some of the best financing options in the country. The keys are knowing the difference between a VA loan and an ODVA loan, understanding your entitlement, and working with people who truly know how to serve veterans. Ask questions, use your benefits wisely, and you'll be in a strong position in Portland's market.
If you're thinking about buying, you don't have to do it alone. Call or text me at 503.997.4169 for a free consultation, and let's put your benefits to work for you.
Ready to Start Your Home Search?
Browse homes in the Portland metro and across the river in Vancouver, Camas, and Ridgefield.
Quick Answers
What is the difference between a VA loan and an ODVA loan?
A federal VA loan is guaranteed by the U.S. Department of Veterans Affairs, needs no down payment with full entitlement, has no monthly mortgage insurance, and works for 1 to 4 units anywhere in the U.S. An ODVA loan is funded and serviced by the Oregon Department of Veterans' Affairs, is for owner occupied single family homes in Oregon only, finances up to 95% of the price, and requires private mortgage insurance above 80%.
How much down payment does an ODVA loan require?
ODVA lends up to 95% of the purchase price or appraised value, whichever is lower, so plan on at least 5% down. Loans above 80% require private mortgage insurance. Gift funds are allowed.
Does ODVA have a minimum credit score?
No. ODVA does not set a minimum credit score. Credit is one part of its underwriting, which follows Fannie Mae guidelines. The federal VA doesn't set a minimum either, but most VA lenders look for about 620.
Does a federal VA Certificate of Eligibility make me eligible for an ODVA loan?
No. ODVA has its own service criteria, and you must apply for ODVA eligibility separately, even if you already have a federal COE.
What is the ODVA loan limit in 2026?
ODVA loans go up to the Fannie Mae conforming limit, which is $832,750 in 2026, or 95% of the price or appraised value, whichever is less.
How many times can I use an ODVA home loan?
Up to four times in your life, with only one ODVA loan open at a time. ODVA loans are purchase only and can't be used to refinance.
What is the VA funding fee in 2026?
For a purchase with less than 5% down, it's 2.15% the first time and 3.3% after that. It drops to 1.5% with 5% down and 1.25% with 10% down. Veterans receiving VA compensation for a service connected disability don't pay it.
Can I buy a duplex or fourplex with a VA loan in Portland?
Yes. A federal VA loan can buy up to four units with zero down if you live in one of them. ODVA loans are for single family homes only.
Is a pest inspection required for a VA loan in Oregon?
Not on every loan anymore. A wood destroying insect inspection is only required if the VA appraiser sees signs of active pests or damage. A full home inspection is still strongly recommended.
Can I use my VA loan in Vancouver or SW Washington?
Yes. The federal VA loan works anywhere in the U.S. The ODVA loan only works for homes in Oregon.
More Guides for Veteran Buyers
Meet Your Veteran Realtor
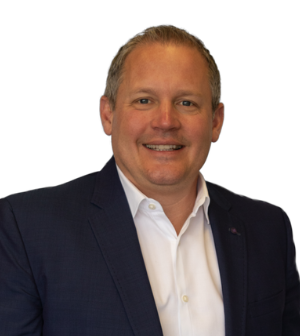
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call, text, or email? 503.997.4169 · Text Us · troy@nwrealtysource.com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. This page is general information, not legal, tax, or lending advice.