Home › Articles and News › What Every Veteran Homebuyer Needs to Know About VA Loans Before Retirement
What Every Veteran Homebuyer Needs to Know About VA Loans Before Retirement
Planning your next chapter in Portland and SW Washington

For many veterans approaching retirement, owning the right home becomes more important than ever. Whether you plan to relocate, downsize, move closer to family, or finally settle into your long term home in the Portland area or SW Washington, understanding your VA loan benefit gives you a major advantage.
VA Loans Are Still One of the Best Benefits You Earned
$0 Down Payment
Many veterans can buy without a large down payment.
No Monthly PMI
VA loans don't require monthly mortgage insurance.
Competitive Rates
VA financing often offers lower rates than many conventional loans.
Flexible Guidelines
VA loans can offer more flexible credit and income standards.
Multi Unit Options
You may be able to buy up to a four unit property and live in one unit. See buying a duplex with a VA loan.
Reuse Your Benefit
VA loan eligibility can be used again and again throughout your life.
For veterans preparing for retirement, keeping more cash in reserve instead of tying it up in a down payment can be a big financial advantage.
1. VA Buyers Are Strong Buyers
One of the biggest myths in real estate is that VA buyers are weaker buyers. That simply isn't true.
- VA loans often close just as fast as conventional financing
- Many VA purchases close in about 30 days
- Veterans often have stable retirement income, pensions, disability income, or reserves
- Experienced listing agents know VA financing can be just as solid as conventional
A properly structured VA offer can compete very well in today's market.
2. You May Be Able to Buy Again Without Selling
Many veterans don't realize they may still have remaining VA entitlement. That flexibility may let you:
- Buy a retirement home before selling your current one
- Keep your current home as a rental
- Relocate to Oregon or Washington while still owning a home elsewhere
Every situation is different. Learn how entitlement works in my VA home loan guide.
3. VA Appraisals Are Designed to Protect You
Another common misconception is that VA appraisals kill deals. In reality, the appraisal helps protect you from overpaying for a home with major safety or value problems. It looks at safety, structural soundness, fair market value, and livability.
The VA's Tidewater process can also give your agent a chance to support the value before a low appraisal is finalized. See VA appraisal requirements.
4. Assumable VA Loans Could Be a Big Opportunity
Many homeowners are locked into lower rates from previous years, so assumable VA loans are becoming more important. In some cases, a buyer can take over an existing VA loan at its lower rate instead of getting a new mortgage at today's rates:
- Potentially lower monthly payments
- Less interest over the life of the loan
- A possible advantage when you sell later
The process can take longer, but the savings can be significant. See Portland VA assumable homes.
5. Plan Ahead Before You Retire
If you plan to retire in the next few years, now is the time to prepare. Review:
- Your current VA eligibility
- Disability and retirement income documentation
- Timing your retirement and your purchase
- Your future monthly housing budget
- Property taxes and insurance costs
- Whether downsizing or relocating makes sense
Disabled veterans in Oregon may also qualify for a property tax exemption. The earlier you start planning, the smoother the move.
Thinking about your next move? Whether you're downsizing, relocating, buying your forever home, or exploring your VA loan options, let's put together a game plan. Call 503.997.4169 or schedule a free call.
Keep Reading
Military Retirement Home Buying
Buying your next home as you retire from the service.
Read the guide ›Veteran Downsizing Guide
Planning a smaller home for retirement, step by step.
Read the guide ›Senior Veteran Home Buying (SRES)
Help for senior veterans buying, selling, or right sizing.
Learn more ›Portland VA Assumable Homes
Take over a seller's VA loan at a lower rate.
Learn more ›Ready to Start Your Home Search?
Browse homes in the Portland metro and across the river in Vancouver, Camas, and Ridgefield.
Frequently Asked Questions
Can I use a VA loan to buy a retirement home?
Yes. The VA loan works for retirement homes as long as you'll live in the home as your primary residence. Many retirees use it to keep more cash in reserve instead of making a large down payment.
Can I buy a new home before selling my current one?
Possibly. If you have remaining VA entitlement, you may be able to buy your next home while you still own your current one. A VA lender can check your entitlement and whether you qualify for both payments.
Do VA loans take longer to close?
Usually not. Many VA purchases close in about 30 days, similar to conventional loans, when the offer and timeline are structured well.
Can I use my VA loan benefit more than once?
Yes. VA loan eligibility can be reused throughout your life. Selling a home and paying off the VA loan typically restores your entitlement.
More Guides for Veterans
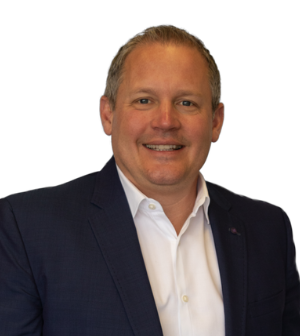
Meet Your Veteran Realtor
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call, text, or email? 503.997.4169 · Text Us · troy [at] nwrealtysource [dot] com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP®, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. This page is general information, not legal, tax, or lending advice.