Home › Video Blog › What Your Portland Home Is Actually Worth in 2026
Video Blog • SellingWhat Your Portland Home Is Actually Worth in 2026: A Veteran Homeowner's Guide
An online estimate is a starting point, not a price. Here is how to find what your home is really worth, and why that number matters so much when your next move uses a VA loan.
Prefer YouTube? Watch this video on YouTube.
Key Takeaways
- Online estimates can't see your upgrades, layout or condition.
- Recent sold comps tell you what buyers actually paid.
- A CMA pulls sales, competition and condition into one realistic number.
- Your true equity shapes your next VA purchase and your PCS timing.
National Headlines Don't Set Your Price
Home prices are projected to rise in many markets in 2026, but whether your home benefits from that depends on where you are and how your home is positioned. Your local market sets your price, not a national forecast.
I talk with homeowners all the time who tell me they checked Zillow, so they know what the house is worth. I understand why. It's quick and it gives you a number right away. But in a market where every neighborhood can move differently, one automated estimate can cost you thousands. Sometimes those numbers are close. Other times they aren't in the ballpark.
“National headlines don't set your home's price. Your local market does.”
Online Tools Are a Reference Point, Not a Strategy
Tools like Zillow's Zestimate or HomeLight's estimator pull from public records and recent sales to produce a quick figure. That can be a useful starting point. But those tools can't see your upgrades, your layout, your maintenance, or the overall condition of your home.
Treat that number as a reference point. It isn't a pricing strategy, and it shouldn't be the number you plan your next move around.
Comparable Sales Tell the Real Story
The next step is recent comparable sales, often called comps. That means three to five similar homes that sold in your neighborhood in the last 90 to 180 days, with similar square footage, age, layout and condition.
Sold homes show what buyers were actually willing to pay, which makes them far more useful than what's currently listed. This is also where working with a real estate professional matters, because most public websites don't show price reductions, buyer concessions, or the market conditions behind the final sale price.
Condition and Layout Move the Number
Two homes with the same square footage can sell for very different prices. Renovated kitchens, updated bathrooms and well maintained systems add value, while needed repairs or dated finishes pull it down.
Layout matters too. Today's buyers pay close attention to functional space, home office potential and overall flow, not just total square footage.
A CMA Brings It All Together
A Comparative Market Analysis, or CMA, combines recent sales, current competition, your home's condition and real-time buyer demand into a realistic value and a pricing plan.
If you need a formal valuation for a refinance or legal purpose, a licensed appraiser can provide one based on an in-person inspection. But if your goal is to understand your value and plan your next move, a CMA gives you accurate numbers and a strategy built for your local market.
Why Your Real Value Matters to Veteran Homeowners
Your Equity Funds the Next Move
Your sale proceeds often cover closing costs, moving expenses and a cushion for the next home. Knowing your real value tells you how much you'll actually have to work with when you buy again.
Planning a PCS Move
When orders set your timeline, a realistic value helps you decide whether to sell now or keep the home. After living in a VA-financed home, many veterans keep it as a rental when they PCS and buy again with remaining entitlement.
Buying Again With a VA Loan
With full entitlement, eligible buyers can purchase with no down payment and no monthly mortgage insurance. Knowing your equity helps you decide how much to put down, if anything, on the next home.
Selling to a VA Buyer
A VA appraisal has to support the price. If the value may come in low, the appraiser notifies the agent, who gets 2 business days to send more comps, so pricing with solid comps from day one protects your sale.
Questions Veterans Ask
Is a Zestimate accurate enough to plan my next VA purchase?
It's a reasonable starting point, but it can't see your upgrades, layout or condition. For planning a move, use a CMA built from recent sold homes on your street.
Do I need a full appraisal to know my home's value?
Not usually. An appraisal is for a refinance or legal purpose. To plan a sale or a PCS move, a free CMA from a local agent gives you the numbers and a strategy.
Should I sell or keep my home as a rental when I PCS?
It depends on your equity, your rent potential and your plans. Many veterans keep a VA-financed home as a rental after living in it and buy again with remaining entitlement, so let's run both options with your real value.
Keep Watching

 Are Home Prices Going to Drop in 2026?
 VA Home Loan Benefits for Veterans in Portland Metro
 What Are the Must-Disclose Items When Selling Your Home in 2026?
 How to Sell Your Home AND Buy Another at the Same Time
 Is the Portland Housing Market Slowing Down or Taking Off? (2026 Update)
 How Can You Make Your Home Irresistible to Buyers?
Want to Know What Your Home Is Really Worth?
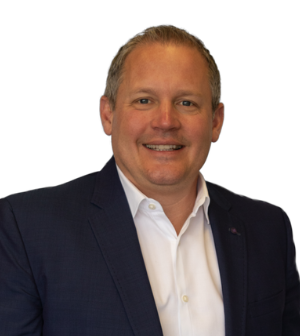
I'm Troy Doty, a Marine Corps veteran and Principal Broker with 25 years and 1,000+ homes sold across the Portland metro and SW Washington. I'll prepare a personalized value analysis from recent sales, current buyer activity and your home's features, so you have clear numbers and a smart plan for your next move.
Schedule a Call503.997.4169Portland Veteran Homes is a private, veteran owned real estate company and is not affiliated with the U.S. Department of Veterans Affairs. Information is general and not legal, tax or lending advice.