Buyer Resource Center › The Home Buying Process › What's a CMA?
Before you make an offer, you want to know what the home is really worth. That's where a comparative market analysis, or CMA, comes in. A CMA compares the home you're considering with similar homes that recently sold nearby, so your offer is based on real market data instead of a guess. Here's how it works and why it matters.
5 Things to Know About a CMA
What a CMA Is
A CMA is a report your agent prepares using recent sales of similar homes, often called comparables or comps. It looks at size, age, condition, location, and features to estimate a realistic price range for the home you want to buy.
How Comparable Homes Are Chosen
The best comps are close by, recently sold, and similar in size, style, age, and condition. In the Portland metro, a few blocks or a school boundary can change values, so local knowledge matters as much as the data.
Adjusting for Differences
No two homes are identical, so the CMA adjusts for differences like an extra bathroom, a remodeled kitchen, a garage, or a busy street. Those adjustments turn a list of sales into a realistic value range.
How It Shapes Your Offer
A CMA tells you whether a home is priced fairly, high, or low compared with the market. Along with days on market and competition, it helps you decide how much to offer and how much room you have to negotiate.
CMA vs Appraisal vs Online Estimates
An appraisal is a formal valuation ordered by your lender, and on a VA loan it also checks minimum property requirements. Online estimates use automated data and can be far off. A CMA bridges the gap with local, hands on analysis before you offer.
The bottom line: Paying the right price starts with knowing the market. A careful CMA protects you from overpaying, strengthens your negotiation, and helps your VA appraisal go smoothly. I'll prepare one for every home you seriously consider.
Frequently Asked Questions
What does CMA stand for in real estate?
CMA stands for comparative market analysis. It's a report comparing a home with similar homes that recently sold nearby to estimate its market value.
Is a CMA the same as an appraisal?
No. A CMA is prepared by a real estate agent to guide pricing and offers. An appraisal is a formal valuation by a licensed appraiser, ordered by the lender. On a VA loan, the appraisal also checks VA minimum property requirements.
How accurate are online home value estimates?
They can be useful as a starting point but are often off, sometimes by a lot, because they can't see a home's condition, updates, or neighborhood details. A CMA from a local agent is usually more reliable.
Does a CMA cost anything for buyers?
Not when you work with me. I prepare CMAs as part of my service before you make an offer.
How recent should comparable sales be?
Ideally within the last three to six months. In a fast changing market, the most recent sales and pending sales carry the most weight.
What if the CMA says a home is overpriced?
That gives you leverage. We can offer below asking, ask for seller concessions, or keep looking. The CMA helps you make that decision with confidence.
Keep Reading
Follow Local Real Estate Trends
Reading the Portland and SW Washington market like a pro.
Read more ›Winning in a Competitive Market: Low Inventory and Multiple Offers
How to compete when homes are scarce, without overpaying or waiving key protections.
Read more ›The Real Estate Negotiating Process
Offers, counteroffers, and how a deal comes together.
Read more ›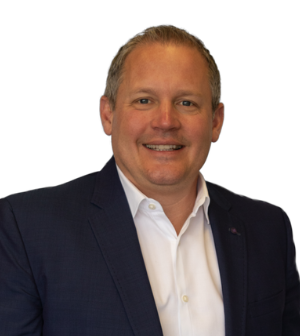
Meet Your Veteran Realtor
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call or email? 503.997.4169 · troy@nwrealtysource.com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. Content adapted in part from ABR® consumer resources. This page is general information, not legal, tax, or lending advice.