Buyer Resource Center › The Home Buying Process › Renting vs Buying
Renting and buying both have their place. The right answer depends on your monthly budget, how long you plan to stay, and how much flexibility you need. For veterans and military families, the VA loan changes the math in a big way, because it removes the down payment that keeps many renters from buying. Here's how to compare the two honestly.
6 Ways to Compare Renting and Buying
Your Monthly Cost
Compare your rent to the full cost of owning, including principal, interest, property taxes, insurance, any HOA dues, and a budget for maintenance. In many parts of the Portland metro and SW Washington, a mortgage payment can be close to rent for a similar home.
Building Equity
Rent pays your landlord's mortgage. A mortgage payment builds your own equity every month as you pay down the loan, and you benefit when your home's value rises over time.
Upfront Costs
Buying usually requires cash for a down payment and closing costs, while renting requires a deposit and first month's rent. The down payment is the biggest hurdle for most first time buyers.
Flexibility and Moves
Renting makes it easy to move on short notice. Buying makes the most sense if you expect to stay for several years, since the costs of buying and selling take time to recover.
Maintenance and Control
Renters call the landlord when something breaks. Owners pay for repairs, but they also get to paint, remodel, add a fence for the dog, or plant a garden without asking permission.
Rising Rents vs a Fixed Payment
Rents tend to rise over time. With a fixed rate mortgage, your principal and interest payment stays the same for the life of the loan, though taxes and insurance can change.
For Veteran Investors
Thinking About a Duplex, Triplex, or Fourplex?
Your VA loan can buy a building with up to four units with no down payment, as long as you live in one of them. Rent from the other units helps cover the mortgage, and it's one of the best wealth building moves a veteran can make. As a Certified Investor Agent Specialist (CIAS™), I help you run the numbers before you ever write an offer.
Buying a Duplex With a VA Loan Free Investment CalculatorThe bottom line: Renting is the right call for some people, especially if you'll only be in the area a short time. But if you plan to stay a few years, or would keep the home as a rental, a VA loan often makes buying the stronger choice. Let's run the numbers on your situation together.
Frequently Asked Questions
Is it cheaper to rent or buy in Portland?
It depends on the home, the neighborhood, and how long you'll stay. A mortgage payment is often close to rent for a similar home, and buying builds equity. The cost of buying and selling means it usually makes the most sense if you plan to stay several years.
How long should I plan to stay to make buying worth it?
A common rule of thumb is at least three to five years, but it depends on prices, rates, and whether you'd keep the home as a rental if you move.
Can I use my BAH to pay a mortgage?
Yes. BAH is yours to use for housing however you choose, including a mortgage payment. Lenders can count it as income when you qualify for a VA loan.
Do I need a down payment to buy instead of rent?
Not with a VA loan. Eligible veterans and service members can buy with no down payment and no monthly mortgage insurance. You'll still want some cash for earnest money, inspections, and reserves.
What if I have to move after I buy?
You can sell, or keep the home and rent it out. Many military families keep their first home as a rental, and depending on your remaining entitlement, you may be able to use your VA benefit again for the next home.
Is a duplex a good alternative to renting?
For many veterans, yes. With a VA loan you can buy a duplex, triplex, or fourplex with no down payment, live in one unit, and use rent from the others to help cover your mortgage.
Keep Reading
15 Ways to Save Money for a Down Payment
Even with a zero down VA loan, cash for closing costs and reserves helps.
Read more ›5 First Time Homebuyer Tips
Smart first steps for veterans buying their very first home.
Read more ›5 Factors to Help Define Your Ideal Home
Get clear on what you really need before you start touring.
Read more ›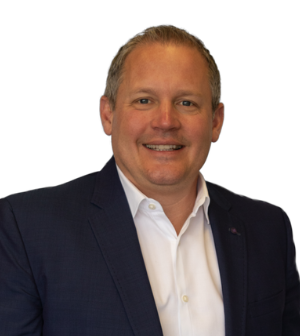
Meet Your Veteran Realtor
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call or email? 503.997.4169 · troy@nwrealtysource.com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. Content adapted in part from ABR® consumer resources. This page is general information, not legal, tax, or lending advice.