Senior Veteran Resource Center › Planning Finances › Home Financing and Planning After 55
Many people assume getting a mortgage gets harder, or even impossible, later in life. It doesn't have to. Whether you're downsizing, moving closer to family, or buying a home that's easier to live in, you have more financing options than you might think. Here's what senior veterans and their families in the Portland and Vancouver area should know.
6 Things to Know About Financing a Later in Life Move
You're Never Too Old for a Mortgage
Federal law prohibits lenders from denying a loan because of your age. A 70 year old can take out a 30 year mortgage just like a 35 year old, as long as they meet the lender's income and credit guidelines.
Retirement Income Can Qualify You
Social Security, pensions, military retirement pay, VA disability compensation, annuities, and regular retirement account withdrawals can all count as income. Some loan programs can also consider your savings and investments when qualifying.
Your VA Entitlement Can Be Restored
If you used your VA loan before, selling that home and paying off the loan restores your full entitlement. If you paid it off and kept the home, a one time restoration may be available. Veterans receiving VA disability compensation are generally exempt from the funding fee.
You Can Buy Before You Sell
Moving twice is hard at any age. Options include a bridge loan or home equity line on your current home, an offer contingent on selling, or negotiating a rent back after you sell so you have time to move.
A Reverse Mortgage Can Buy a Home
A Home Equity Conversion Mortgage for Purchase lets homeowners 62 and older buy a new home with a larger down payment and no required monthly mortgage payment. You still pay property taxes, insurance, and upkeep, and the loan is repaid when you sell or move out.
Cash vs Keeping a Mortgage
Paying cash avoids a monthly payment, but ties up money you may want for travel, care, or emergencies. A modest mortgage can keep savings available. The right answer depends on your income, taxes, and goals.
Meeting With a Financial Advisor
A good advisor can help you decide how your home fits into your retirement plan. Here's how to get the most from the meeting.
Know What You Want
Write down your goals, like paying cash for a smaller home, keeping a mortgage, leaving an inheritance, or covering future care.
Bring Your Numbers
Recent statements for income, pensions, Social Security, VA benefits, savings, debts, and your home's estimated value.
Ask About Fiduciary Duty
Ask whether the advisor is a fiduciary who must act in your best interest at all times.
Understand Fees
Advisors may charge a flat fee, an hourly rate, a percentage of assets, or commissions. Ask for fees in writing.
Check Credentials
Look up an advisor's background through FINRA BrokerCheck or the SEC's adviser search, and ask about designations like CFP®.
Include Your Spouse or Family
Bring the people who will help carry out the plan, so everyone hears the same advice.
The bottom line: Age isn't a barrier to buying a home. Retirement income can qualify you, your VA benefit can be used again, and options like a bridge loan or reverse mortgage for a purchase can make the move easier. Talk with a VA experienced lender and a trusted financial advisor, and I'll help you put the real estate side together.
Frequently Asked Questions
Can I get a mortgage at 70 or older?
Yes. Lenders can't deny a loan because of your age. You'll need to meet the same income, credit, and debt guidelines as any other borrower.
Does Social Security count as income for a mortgage?
Yes. Social Security, pensions, military retirement pay, and VA disability compensation can all count as income when you apply for a mortgage.
Can I use my VA loan again to downsize?
Yes. Selling your current home and paying off the VA loan restores your entitlement, and there's no age limit on the benefit.
What is a reverse mortgage for purchase?
It's a Home Equity Conversion Mortgage that lets buyers 62 and older purchase a home with a larger down payment and no required monthly mortgage payment. Taxes, insurance, and upkeep still must be paid.
Should I pay cash for my next home?
It depends. Paying cash eliminates a payment but reduces your savings. Many retirees keep a modest mortgage to stay flexible. A financial advisor can help you decide.
How do I choose a financial advisor?
Ask whether they're a fiduciary, how they're paid, and what credentials they hold. You can check their background through FINRA BrokerCheck or the SEC's investment adviser search.
Search Homes in Portland and SW Washington
Start with single level homes, or browse condos and homes near family across the Portland metro, or across the river in Vancouver, Camas, and Battle Ground. Save your favorites and I'll help you narrow them down.
More Veteran Guides on This Site
Keep Reading
Long-Term Care Options and Costs for Veterans
Care options, what they cost, and the VA and state programs that help pay.
Read more ›Decluttering and Rightsizing the Family Home
What to keep, sell, donate, or pass on, and how to make downsizing easier.
Read more ›55+ and Active Adult Communities in Portland and Vancouver
Pros, cons, renting vs buying, and the questions to ask before you commit.
Read more ›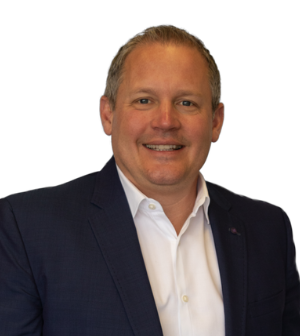
Meet Your Veteran Realtor
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call or email? 503.997.4169 · troy@nwrealtysource.com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. Content adapted in part from SRES® consumer resources. This page is general information, not legal, tax, or lending advice.