Buyer Resource Center › Before You Buy › 5 FAQs About Condo Insurance
Insuring a condo works differently from insuring a house. Your association carries a master policy on the building, and you carry your own policy for everything else. Knowing where one ends and the other begins protects you from costly gaps. Here are the five questions I hear most.
Your 5 Condo Insurance Questions, Answered
What Does the Association's Master Policy Cover?
The master policy typically covers the building's structure, common areas, and shared liability. Some policies cover only the bare walls, while others include original fixtures and finishes inside each unit. Ask for the master policy summary so you know which type you're buying into.
What Does My Own Condo Policy Cover?
A condo policy, often called an HO-6, covers the inside of your unit that the master policy doesn't, like flooring, cabinets, and upgrades, plus your personal belongings, liability, and extra living expenses if you have to move out during repairs.
What Is Loss Assessment Coverage?
If the master policy has a large deductible or a claim exceeds its limits, the association may bill owners for their share. Loss assessment coverage on your policy can help pay that bill.
Do I Need Earthquake or Flood Coverage?
Standard policies generally exclude earthquakes and floods. In the Pacific Northwest, earthquake coverage is worth discussing, and flood coverage may be required if the building is in a flood zone. Check whether the master policy includes either.
What Will My Lender Require?
Lenders require proof that the building is adequately insured through the master policy. Many also require you to carry your own condo policy, especially if the master policy covers only bare walls.
The bottom line: Condo insurance is about filling the gaps between the master policy and your unit. Know which type of master policy the building has, carry enough coverage for your interior and belongings, add loss assessment coverage, and think seriously about earthquake protection here in the Northwest.
Frequently Asked Questions
What is an HO-6 policy?
It's insurance designed for condo owners. It covers the interior of your unit, your personal property, liability, and additional living expenses, filling the gaps the association's master policy doesn't cover.
Is condo insurance required?
Many lenders require it, particularly when the master policy covers only bare walls. Even when it isn't required, it's strongly recommended to protect your belongings and finishes.
What's the difference between bare walls and all in master policies?
A bare walls policy covers the structure but not interior finishes. An all in policy also covers original fixtures and finishes inside units. Your own policy should cover whatever the master policy doesn't.
What is loss assessment coverage?
It helps pay your share if the association bills owners for a large deductible or a loss that exceeds the master policy's limits.
Does condo insurance cover earthquakes in Oregon and Washington?
Usually not. Earthquake coverage is typically an add on or a separate policy. Check what the master policy includes and consider coverage for your unit.
How much does condo insurance cost?
It depends on the building, location, coverage limits, and deductible. Getting quotes from a few insurers is the best way to compare.
Keep Reading
Buying a Condo: Pros, Cons, and Questions to Ask
Lifestyle trade offs, HOA questions, and VA approval for Portland area condos.
Read more ›How to Evaluate an HOA
Dues, reserves, and rules to review before you commit.
Read more ›4 FAQs About Closing
Who's there, what you sign, and what to bring on closing day.
Read more ›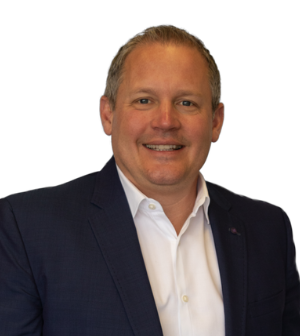
Meet Your Veteran Realtor
Troy Doty, Principal Broker
Troy Doty is a Principal Broker with Northwest Realty Source in Portland, with 25 years in real estate and over 1,000 homes sold across the Portland metro and SW Washington. As a Marine Corps veteran, Troy has a true passion for helping Portland veterans and active duty military families buy and sell homes, whether you're PCSing in, transitioning out, buying your first home, investing in a duplex, triplex, or fourplex, or right sizing later in life.
Schedule a Call or Video Meeting ➜ More About Troy ➜ Free Veteran Buyer E-BookPrefer to call or email? 503.997.4169 · troy@nwrealtysource.com
Troy Doty, Principal Broker, Northwest Realty Source. Licensed in Oregon and Washington. ABR®, MRP, and SRES® are credentials of the National Association of REALTORS® and its affiliates. CIAS™ is a designation of U.S. Realty Training. Content adapted in part from ABR® consumer resources. This page is general information, not legal, tax, or lending advice.